

How Much Insurance Do I Need When I Buy a Home?
 Written by Preston Micalizio Preston MicalizioPreston Micalizio writes insurance content for SmartFinancial. He brings three years of professional experience writing ... Read more |  Edited by Dylan Tate Dylan TateDylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health a... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
It’s generally recommended that you purchase enough homeowners insurance to replace your home and belongings after a total loss and to protect yourself in case major liability concerns arise. Depending on where you live, you may also want to purchase extra coverage types to insure your home against perils that aren’t ordinarily covered by home insurance, like floods and earthquakes.
Keep reading for an overview of all the factors you should consider when deciding how much home insurance you need.
|
Key Takeaways
|


How Do I Determine How Much Home Insurance I Need?
When determining how much homeowners insurance you should have, consider whether you are willing to pay a higher premium in exchange for more thorough coverage. For example, you may be able to insure your personal property with replacement cost value (RCV) coverage, meaning your insurance company will pay you whatever it costs to replace a lost item with a comparable new item.
However, you could pay less for a policy that only insures your belongings at their actual cash value (ACV), meaning money would be deducted from your payout based on depreciation factors, like age or wear and tear, after a covered loss.
Although an ACV policy provides less coverage than an RCV policy, you may still prefer it, depending on your priorities. For example, if you own several items you don’t feel obligated to replace if they are destroyed, you might opt for an ACV policy that allows you to pay lower premiums.
How Do I Choose the Right Home Coverage?
When you set your home insurance limits, you’ll need to think through how much coverage you want for each category of insurance. Homeowners insurance policies typically include six coverage types: dwelling, other structures, personal property, loss of use, personal liability and medical payments.

Dwelling
Dwelling coverage insures the structure of your home and any attached structures. In general, you will want enough dwelling coverage to rebuild your home in case of a total loss. As a result, you should research material and labor costs for construction projects in your area and consider if your house has any renovations that would impact the cost of rebuilding before deciding how much dwelling coverage you should buy.
An additional coverage option you can consider is extended replacement cost coverage, which may extend your policy limits by up to 50% in case you need more money to rebuild your house. For example, if you buy $250,000 worth of dwelling coverage, you may get an extra $125,000, if necessary, through your extended replacement cost coverage. Some insurers may also offer guaranteed replacement cost coverage that comes without a coverage limit and instead pays to rebuild your house regardless of the cost.[1]
For example, ordinance or law coverage can pay for any extra costs associated with bringing your new home up to local building codes. Meanwhile, inflation guard coverage ensures your coverage limits will automatically adjust to account for inflation, typically by a set percentage every few months or longer.[2]
Other Structures
Other structures coverage insures structures on your property that aren’t connected to your home, such as sheds and fences. For the most part, homeowners insurance policies set your other structures coverage limit at 10% of your dwelling coverage limit.[3]
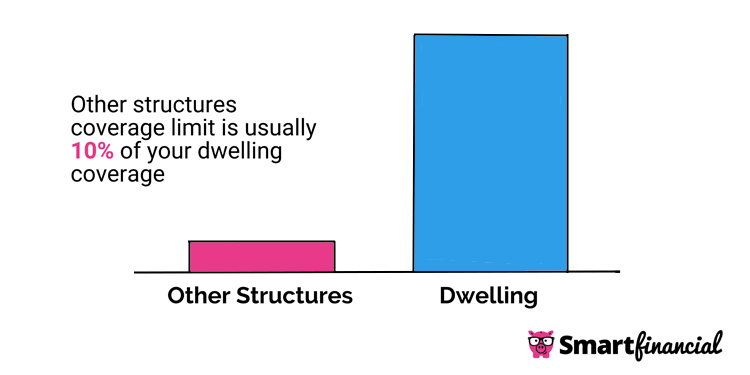
For example, if you select a policy with $250,000 worth of dwelling coverage, you might automatically get $25,000 worth of other structures coverage. However, the exact amount of coverage available can vary based on your insurance company and the details of your policy.
Personal Property
Personal property coverage can reimburse you if your possessions, like clothes, electronics and furniture, are damaged or lost. Many home insurance policies set your personal property coverage limit between 50% and 70% of your dwelling coverage limit. In addition, several insurance carriers offer off-premises coverage that protects your belongings anywhere in the world, with a limit set at 10% of your overall personal property coverage limit.[3]
This means that, if you have $250,000 in dwelling coverage, a typical homeowners policy will provide between $125,000 and $175,000 to cover your personal property, with between $12,500 and $17,500 being available to reimburse you for belongings stolen from your vehicle or other items you lose outside of your home. Of course, you may be able to raise or lower your personal property coverage limits depending on the amount of property you need to insure.
To more precisely determine how much personal property coverage you need, you could consider making a home inventory that documents all of your possessions, when you bought them and how much you paid for them. Keep in mind that your insurance company may enforce a sublimit for valuables like jewelry, so you may want to purchase a scheduled property coverage endorsement to make sure your most expensive items are insured at their full value.
Loss of Use
Loss of use coverage can cover additional living expenses, such as temporary housing, storage and restaurant costs, after your house becomes uninhabitable due to a peril covered by your homeowners insurance. Many policies set your additional living expense coverage limit at 20% of your dwelling coverage limit, but the available limits can vary from insurer to insurer.[4]
When deciding how much loss of use coverage you need, consider how likely you are to need it. For example, if you live in a region that is prone to tornadoes or some other natural disaster that is covered by home insurance and could reasonably destroy your home, it may be worth investing in higher loss of use coverage limits.
Personal Liability
Personal liability coverage can cover medical bills and lost wages for someone injured on your property, repair bills if you are liable for damaging someone else’s property and legal expenses if a bodily injury or property damage claim escalates into a lawsuit. While most policies have a minimum of $100,000 worth of coverage, it’s generally recommended that you buy a policy with personal liability coverage limits in the $300,000 to $500,000 range.[4]
The characteristics of your property will play a role in determining how much personal liability coverage you need. For example, someone with a two-story house may need more liability coverage than someone with a one-story house since the presence of stairs creates an added risk of injury. You will also likely need more coverage if you own an attractive nuisance, like a trampoline or swimming pool, that could reasonably attract a child to your property and cause them to get injured.
Medical Payments
Medical payments coverage pays for someone else’s medical treatments after they are injured on your property, regardless of who is at fault. However, it doesn’t cover legal expenses. Medical payments coverage typically has a low maximum limit, as you may only be able to buy up to $5,000 worth of coverage.[5]
Are Certain Types of Home Insurance Policies Required?
You are not legally required to purchase homeowners insurance in any state. However, your lender will likely require you to buy home insurance if you take out a mortgage to pay for your house. If you have paid off your house, it is entirely up to you whether you decide to keep your homeowners insurance.
Can I Drop Coverage I Don’t Need?
A standard homeowners insurance policy automatically includes the six main coverage types mentioned above, and you may not be able to completely remove them from your policy, depending on your insurer. For example, even if your home is the only standalone structure on your property, your insurance company may not allow you to drop your other structures coverage since it’s part of the standard home insurance package.[6]
However, if you have added extra coverage to your policy through insurance riders, you may be able to get rid of these coverage types later. For example, if you want to lower your homeowners insurance premium, you could drop your extended replacement cost coverage or scheduled property coverage.
Home Insurance Coverages To Consider
In the following sections, you’ll learn about optional coverage types you can purchase to raise your coverage limits for certain losses or make up for the exclusions that your basic home insurance policy won’t cover.
Excess Liability
Excess liability coverage is an optional home insurance add-on that kicks in if you need to file a liability claim that exceeds your personal liability coverage limit. A type of excess liability coverage known as umbrella insurance may provide coverage for more situations than your personal liability insurance and can apply to multiple policies at once, meaning it could cover large claims for both your homeowners and car insurance policies.
Not everyone needs umbrella insurance. In fact, you might not be eligible for it at all unless you have a minimum of $300,000 in personal liability coverage.[4] However, umbrella policies can provide between $1 million and $5 million in excess liability coverage, making them beneficial for people with a large number of valuable assets that could be targeted in a lawsuit related to a liability claim.[7]
Umbrella insurance can also be useful thanks to the broad range of coverage it provides. For example, the personal liability coverage portion of many homeowners insurance policies won’t cover claims involving dog bites from notoriously aggressive breeds, like pit bulls and Rottweilers, but an umbrella insurance policy may.
Flood
Homeowners insurance generally doesn’t cover flooding unless you purchase flood insurance from either the federal government or a private insurance provider. The Federal Emergency Management Agency’s National Flood Insurance Program (NFIP) offers building and contents coverage, which are similar to a standard home insurance policy’s dwelling and personal property coverage. Through the NFIP, homeowners can buy $250,000 worth of building coverage and $100,000 worth of contents coverage with a $2,500 sublimit on valuables.[8]
Earthquake
You typically won’t be covered for earthquakes unless you purchase separate earthquake coverage. It’s worth noting that, if you live in California, your insurance company is required to offer you earthquake insurance with the same amount of dwelling coverage as your standard home insurance policy, between $5,000 and $25,000 worth of personal property coverage and between $1,500 and $100,000 worth of loss of use coverage.[9]
Sewer Line Replacement
Standard homeowners insurance policies will only pay for a sewer line replacement if a peril covered by your policy damages your pipes. However, you may be able to insure sewer lines and other underground utility lines against a broader range of perils by purchasing extra coverage. For example, American Family Insurance offers service line coverage that protects against wear and tear, mechanical breakdowns and more with a limit of $10,000 per incident.[10]
How To Get the Right Amount of Home Insurance To Suit Your Needs
After calculating the amount of coverage you need for your home and personal possessions, you should shop around to understand your options. Seek quotes from three to five insurance companies to get a range of available premiums. Ensure you discuss potential savings opportunities you may qualify for, such as discounts for bundling home and auto insurance. You’ll typically need to give information about your home, such as its size, location and age.
Getting quotes can become tedious and time-consuming, as you’ll typically need to go through each insurer individually. However, you can speed up this process using an insurance marketplace like SmartFinancial. After answering a brief questionnaire, we can connect you with a licensed insurance agent to help you get the right amount of home insurance coverage that meets your needs. Click here for a free homeowners insurance quote today!
- Insurance quotes /
- Home /
- How Much Homeowners Insurance Do I Need
Preston Micalizio writes insurance content for SmartFinancial. He brings three years of professional experience writing in various industries, from higher education to e-commerce. He strives to engage with the audience, provide accurate reporting and make complex subjects easily digestible.


Get a Free Home Insurance Quote Online Now.
More on Home Insurance

Looking for Home Insurance?
Compare rates from dozens of companies in less than 3 minutes.