

How To Switch Your Car Insurance Policy
 Written by Preston Micalizio Preston MicalizioPreston Micalizio writes insurance content for SmartFinancial. He brings three years of professional experience writing ... Read more |  Edited by Richard Murphy Richard MurphyRichard Murphy manages content on SmartFinancial's website. With a strong background in content strategy and copywriting... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
If you’re not careful, switching car insurance carriers may result in unexpected cancellation fees or lapses in coverage that can raise your car insurance rates. Losing discounts from your current insurer after you switch can also lead to higher overall insurance costs without you realizing it.
Keep reading to learn how to switch car insurance policies without fees — including how to check your current policy for cancellation charges, shop around and schedule your new policy’s start date.
|
Key Takeaways
|
On This Page

How To Switch Car Insurance
Can I Switch My Car Insurance Policy Any Time?
Are There Fees or Penalties When Canceling and Switching Car Insurance?
Why Do People Switch Car Insurance Companies?
When Would Be the Best Time To Switch a Car Insurance Policy?
When To Avoid Switching Car Insurance Companies?
FAQs

How To Switch Car Insurance
Below, we’ll outline the steps to follow when switching auto insurance companies to help you avoid cancellation fees or coverage gaps.
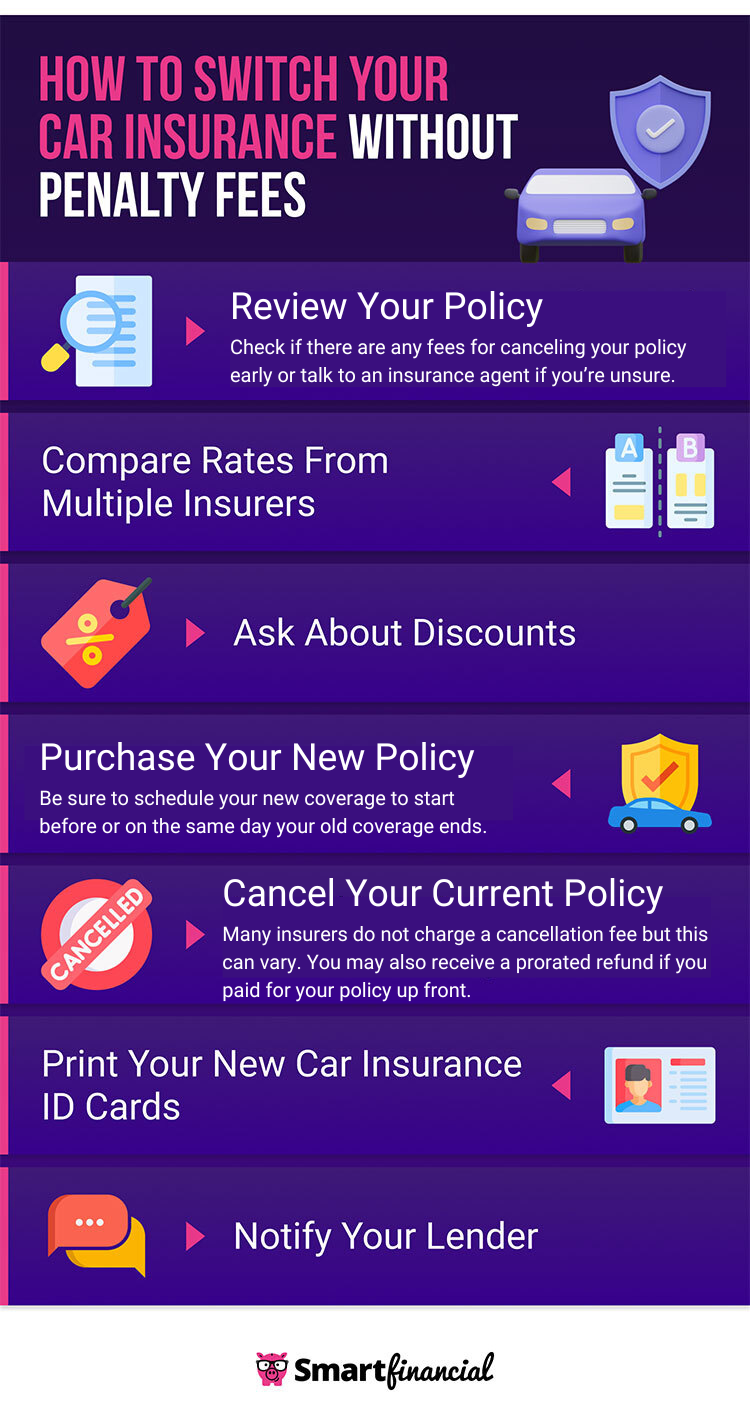
Step 1: Review Your Current Insurer’s Cancellation Policy
Reviewing your cancellation policy will help you decide whether to end your current policy early or wait until it expires. For example, if the cancellation fee for ending your policy before the term ends is higher than the savings from switching, you may want to stay with your current policy for its full term.
When reviewing your policy, find answers to the following questions:
- What is the exact end date of your policy?
- Will you be charged a cancellation fee for ending your policy early?
- Will your current insurer issue a prorated refund if you switch car insurance carriers mid-policy?
If you cannot find the answers to these questions, call your insurance company and ask your agent to explain any consequences of canceling your policy early.
Step 2: Compare Rates From Multiple Insurers
Shopping around may help you find a better deal than what your current insurer offers. You may be surprised how much you’re overpaying for car insurance after reviewing rates in the current market.
When comparing quotes, make sure you’re evaluating equivalent policies. For example, comparing a full coverage quote from one insurer to a minimum coverage quote from another would not be accurate.
Step 3: Ask About Discounts
Once you’ve narrowed down your top options, ask each insurer about available discounts to help maximize your savings. You may qualify for the following:
- Multi-policy discount: Purchase more than one policy from the same carrier, such as auto and home insurance.
- Multi-car discount: Add more than one vehicle to the same auto policy.
- Vehicle safety/anti-theft discounts: Your vehicle includes safety devices, such as anti-lock brakes, airbags and daytime running lights.
- Good driver discount: Maintain a clean driving record with no accidents, tickets or claims for a set period.
- Defensive driver discount: Complete a defensive driving course.
- Affinity discount: Be a member of a qualifying organization, group or profession (e.g., military or teacher).
Step 4: Purchase Your New Policy
After choosing a new policy, buy it and make sure coverage starts before your current policy ends or renews to avoid a lapse in coverage.
Step 5: Cancel Your Existing Insurance Policy
After purchasing your new policy, cancel your old one to avoid being charged if you’re enrolled in auto-renewal. Depending on the insurer, you may be able to cancel online or by phone. Be sure to save a copy of your cancellation confirmation for your records.
If you’re entitled to a prorated refund for canceling mid-term, ask your insurer how it will be issued. You may receive the refund on your card or as a check by mail.
Step 6: Print Your New Car Insurance ID Cards
Most states require a minimum level of car insurance, and your proof of car insurance card proves you meet the state mandates. After buying your new policy, the new insurer should mail you a physical proof of insurance card. Proof of insurance may also be available online or by mobile app, depending on the insurer.
Store your insurance card in a readily accessible area, such as your glove compartment. You may face fines or penalties if you cannot show proof of insurance when an officer pulls you over. Many insurers also offer digital insurance cards.
Step 7: Notify Your Lender
If you are financing your car, your lender technically still owns your car and must be notified of any changes to your insurance. Failing to inform your lender when you switch carriers may lead them to believe you’re not maintaining full coverage.
In that case, the lender may purchase a policy on your behalf — often at a much higher cost — and bill you for it.
Can I Switch My Car Insurance Policy Any Time?
In general, you can switch car insurance carriers at any time, and doing so typically won’t affect your rates. In fact, switching may be beneficial — shopping around can help you find better prices.
Do I Need To Cancel My Car Insurance Policy Before Switching?
No — do not cancel your current policy before your new one begins, as this can result in a lapse in coverage. Even a one-day gap may raise your future insurance rates, since insurers view any lapse negatively.
Are There Fees or Penalties When Canceling and Switching Car Insurance?
While not always common, some car insurance companies may charge a cancellation fee if you end your policy before the term expires. These fees may be a flat dollar amount or calculated using a short rate — charging a percentage of the unused premium.
Early cancellation fees generally range from $20 to $200.[1]
Why Do People Switch Car Insurance Companies?
Shopping around can help you find a more affordable auto policy that better fits your needs. In addition to saving money, certain life events may signal it’s time to switch car insurance carriers. Below are common reasons drivers make the switch:
- Your insurer increased your rates: Premiums may rise after a car accident or if your credit score drops. Another insurer might offer similar or better coverage at a lower rate.
- Your credit score changed significantly: In some states, improved credit could qualify you for lower rates with a different insurer. Even if your credit worsens, another carrier may still offer a more competitive premium.
- Your marital status changed: Married drivers often receive lower rates than single, divorced or widowed individuals. You may qualify for a discount if you recently got married.
- You added or removed a driver from your policy: Adding a driver usually raises your premium, while removing one often lowers it. If your rates increase, switching insurers may help you save.
- You added or removed a vehicle from your policy: Changing the number of vehicles on your policy affects your premium. A different carrier may offer more favorable pricing.
- You purchased your first home: Some insurers offer discounts for homeowners. Bundling auto and home insurance may also unlock additional savings.
- You moved to a different city or state: ZIP codes influence rates due to factors like crime, weather and repair costs. If your insurer doesn’t operate in your new location, you’ll need to find a new provider.
- Your current insurer has poor customer service: If you’re dissatisfied with how a claim was handled, switching carriers could improve your experience.
- You got into a car accident: After a claim, your premium will likely increase. Comparing quotes from other insurers may help you find a better deal.
When Would Be the Best Time To Switch a Car Insurance Policy?
Shopping for car insurance and switching carriers every six to 12 months is generally a good idea. Car insurance policies typically carry six- or 12-month terms, creating a natural timestamp for when it’s time to switch.[2]
Insurance rates constantly shift based on your risk factors and market factors, like inflation and repair costs. Making shopping around a regular habit can help you maintain your desired coverage at the cheapest price.
You may also want to shop around when you experience certain life events. For example, moving into a lower-crime neighborhood may lower your premium if you maintain comprehensive coverage. Or, consider buying a pay-per-mile policy if you switch to a work-from-home position.
When To Avoid Switching Car Insurance Companies?
If you filed a car insurance claim after an accident, your insurer will likely add a premium surcharge when you renew your policy. Other insurers may also consider your recent accident when quoting new rates. Unless you find a lower rate than your current premium despite the accident, it's usually better to stick with your current policy until it expires to avoid paying elevated rates earlier than you have to.
Additionally, always understand how your current discounts will affect your overall costs if you decide to switch carriers. You may not realize that you may be paying more after switching to a new company because you’re losing savings, like bundling discounts or loyalty discounts.
For example, if you have a discount because you’ve bundled homeowners and auto insurance, remember that if you switch to a new auto insurance carrier, losing the bundle discount will cause your home insurance premium to increase.
- Insurance quotes /
- Auto /
- How To Switch Car Insurance
Preston Micalizio writes insurance content for SmartFinancial. He brings three years of professional experience writing in various industries, from higher education to e-commerce. He strives to engage with the audience, provide accurate reporting and make complex subjects easily digestible.


Get a Free Auto Insurance Quote Online Now.
More on Auto Insurance

Looking for Auto Insurance?
Compare rates from dozens of companies in less than 3 minutes.