

Valentine’s Day and Insurance: Protecting Who You Love
 Written by Dylan Tate Dylan TateDylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health a... Read more |  Edited by Richard Murphy Richard MurphyRichard Murphy manages content on SmartFinancial's website. With a strong background in content strategy and copywriting... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
Though insurance may not make for a flashy Valentine’s Day present, it can still be a romantic gesture to make sure the person you love is adequately insured against life’s unexpected events through various policies, like home, auto, health and life insurance. In addition, you shouldn’t purchase extravagant jewelry or plan an overseas getaway without first having appropriate Valentine’s Day insurance policies in place to cover them.
Read on to learn more about the ins and outs of insurance on Valentine’s Day, including which policies are most important and what opportunities you may have to save money on coverage.
|
Key Takeaways
|


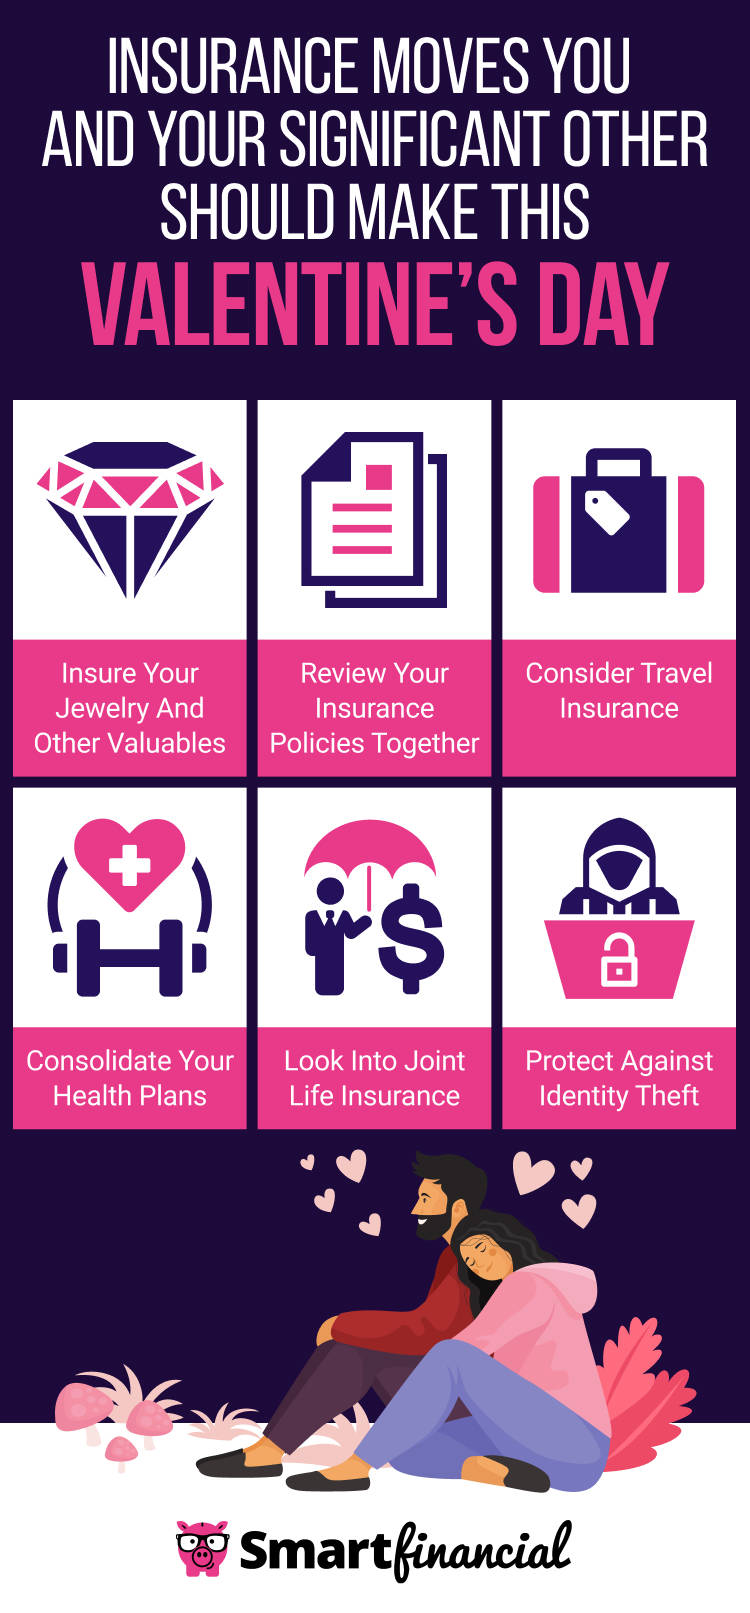
6 Insurance Moves You Should Make on Valentine’s Day
Below, you’ll find overviews of some of the biggest insurance industry considerations you should have in mind heading into this Valentine’s Day.
1. Insure Your Jewelry and Other Valuables
Look into additional coverage options if you plan to buy an expensive ring, necklace or watch for your significant other this Valentine’s Day. Basic renters and home insurance policies often apply sublimits to valuables, so the coverage limit for your jewelry may be lower than your overall personal property coverage limit. For example, Lemonade renters insurance policies will only pay out up to $1,500 for jewelry theft claims — even if your jewelry is worth more than that.[1]
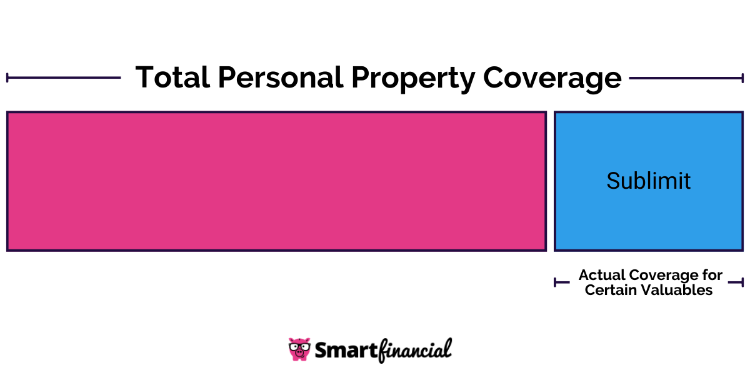
As a result, you may need to purchase a standalone jewelry insurance policy or a scheduled personal property coverage endorsement for your homeowners or renters policy — both of which allow you to secure higher coverage limits for select valuables. These specialized insurance products may even cover perils that aren’t covered by your basic policy, such as accidental damage caused by you and unexplained disappearances.[1]
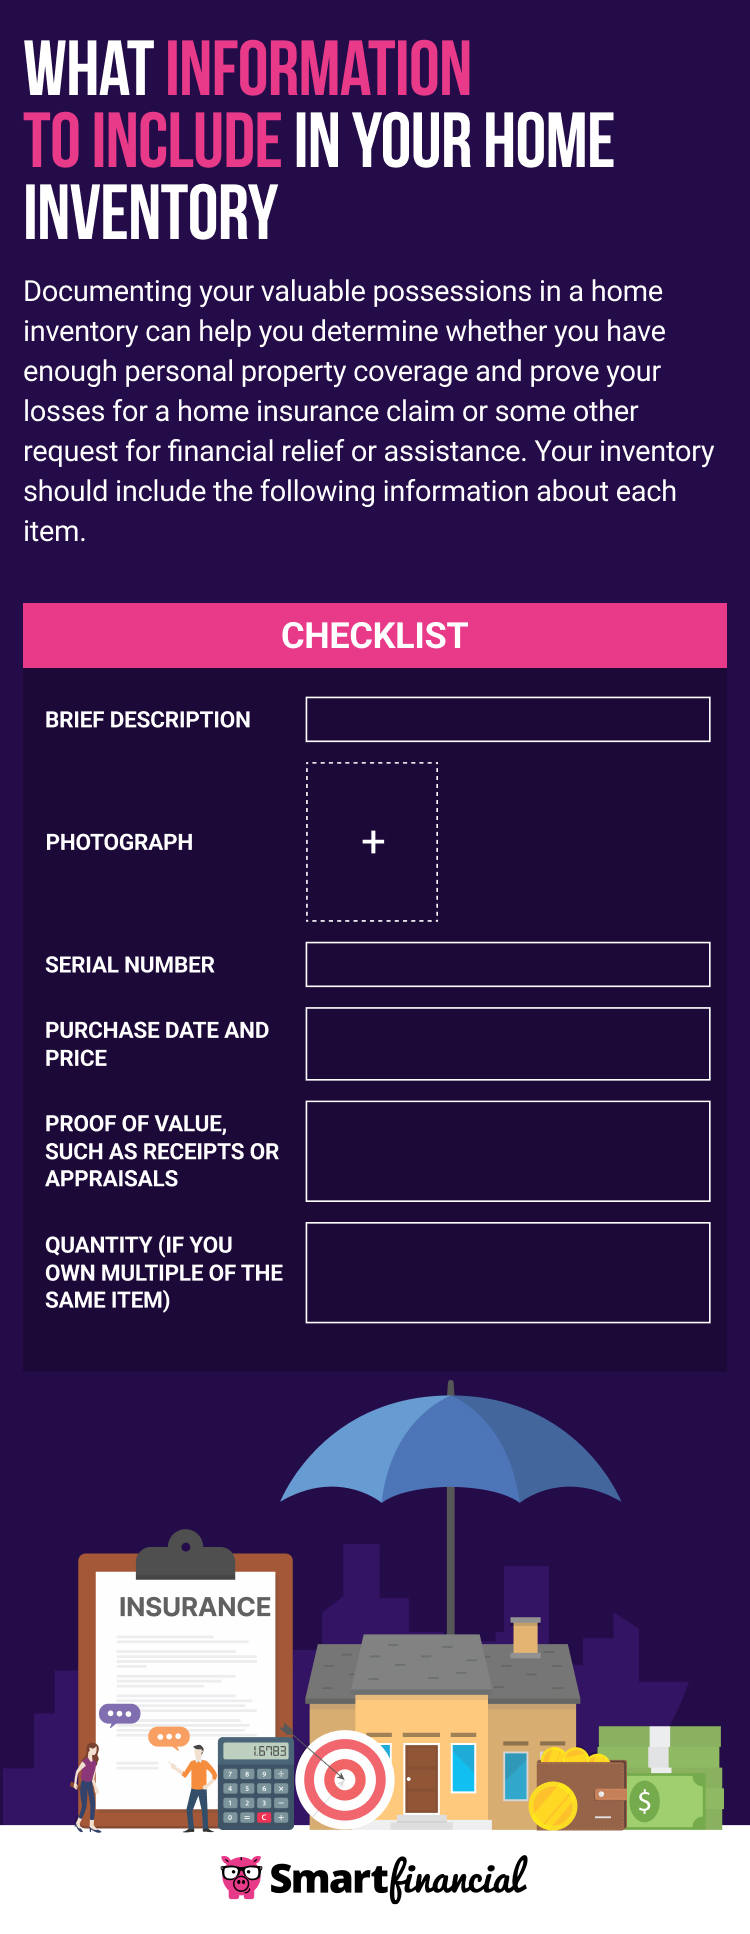
Along with obtaining extra coverage, be sure to update your home inventory after purchasing a highly valuable piece of jewelry. Your home inventory should include documentation of the most valuable items you own and how much they are worth. In the event of a covered peril — like a house fire — you can present your inventory to your insurance company to prove your losses and make sure you are properly reimbursed.
2. Review Your Insurance Policies Together
If you plan to move in with your loved one this Valentine’s Day, go over your insurance policies to ensure you are both properly covered. For example, if your partner is moving into your current house or apartment, you may need to raise your personal property coverage limit to account for their possessions. Meanwhile, you could qualify for a multicar discount by adding both of your vehicles to the same auto insurance policy.[2]
3. Consider Travel Insurance
Travel insurance can be a significant asset for anyone planning a special romantic getaway for Valentine’s Day — especially when it involves traveling abroad. Your travel insurance provider may cover international health care — which likely won’t be covered by your standard health plan — along with other expenses, such as reimbursement for lost luggage or unexpected trip cancellations.[3]
4. Consolidate Your Health Plans
Married couples and, in some cases, unmarried domestic partners may be allowed to join the same health insurance plan — which may be the most cost-effective option, depending on your circumstances. For example, if you are currently paying full price for a Health Insurance Marketplace plan, it may be cheaper to join your spouse’s work-based health plan, since their employer may cover the majority of the premium.
Keep in mind that you can generally only change your health insurance coverage during the once-yearly open enrollment period or a special enrollment period triggered by a qualifying life event. Getting married and moving to a new county or ZIP code count as qualifying life events.[5] However, you may not automatically qualify for a special enrollment period if you move in with your partner who lives in the same city without getting married.
5. Look Into Joint Life Insurance
You and your spouse may be eligible for joint life insurance, meaning both of you can be covered by the same policy. If you opt for first-to-die life insurance, then whenever one of you dies, the surviving spouse will receive a payout to cover final expenses or other costs. Conversely, second-to-die — or survivorship — life insurance pays out a death benefit to other beneficiaries, such as your children, after both you and your spouse have died.[6]
If you plan on starting a family, evaluate whether your life insurance coverage limits are high enough. It’s commonly recommended that you purchase a policy with a death benefit between 10 and 30 times your current salary, depending on your age. However, your coverage needs may vary based on the number of dependents you want to provide ongoing financial security for and the specific expenses you want to help them cover after you die.[7]
6. Protect Against Identity Theft
Another coverage type worth considering is identity theft insurance, which can protect you from severe financial losses if your credit card information is stolen amid a bustling restaurant crowd on Valentine’s Day. Identity theft coverage can reimburse you for legal fees, lost wages and other expenses related to restoring your stolen identity.[8]
Can You Save Money On Insurance on Valentine’s Day?
While insurance companies generally don’t offer discounts specifically related to Valentine’s Day, your insurer may offer discounts that are exclusively available to couples. For example, married couples often get to pay less for car insurance because insurance carriers view them as more financially stable and, therefore, less risky to insure.[9]
Regardless of what insurance discounts you are eligible for, you can always shop around to see if you can find a better deal on the insurance policies you need. SmartFinancial allows you to compare quotes for multiple types of insurance coverage at no charge. Click here to select the type of coverage you need and start comparison shopping today!
- Insurance quotes /
- Valentines Day Insurance
Dylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health and life insurance under his belt. He has over nine years of experience writing for online publications, primarily about gaming and esports. In the process, he has become an expert in search engine optimization, news reporting, feature writing and copy editing.


Get a Free Insurance Quote Online Now.
More on Insurance
Get a Free Insurance Quote.
Compare rates from dozens of companies in less than 3 minutes.