
What Type of Insurance Do I Need for Winter Weather?
 Written by Dylan Tate Dylan TateDylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health a... Read more |  Edited by Richard Murphy Richard MurphyRichard Murphy manages content on SmartFinancial's website. With a strong background in content strategy and copywriting... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
Various types of insurance can provide coverage for weather-related claims and other losses during the winter months, including homeowners, renters, auto and commercial insurance. Fortunately, you shouldn’t need to buy any extra winter insurance policies, since the aforementioned policies should automatically include coverage for many common winter risks.
Keep reading to learn about the most important types of insurance for winter weather and to see examples of the risks that are most likely to lead to winter weather insurance claims.
|
Key Takeaways
|


What Are the Most Common Risks Faced in the Winter?
Read the following sections for examples of the biggest risks different types of property owners and other individuals are likely to encounter in the winter.
Homeowners
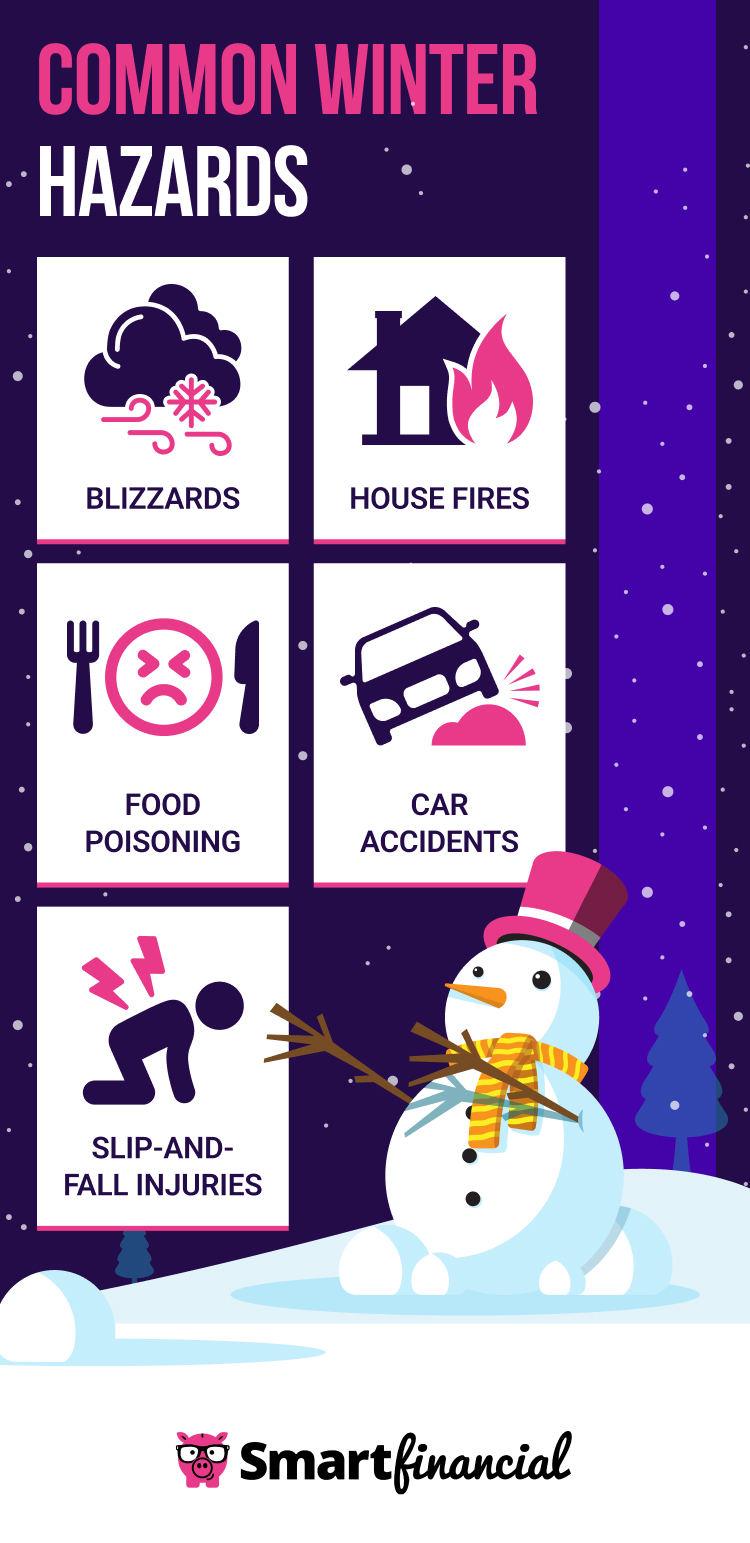
In general, some of the most common risks homeowners face are windstorms, fires and water damage — making winter an especially high-risk season due to the prevalence of hazards like blizzards and frozen pipes.[1] In addition, house fires occur most often in December and January — likely due to an increase in candle use, holiday cooking, Christmas tree fires and other holiday decoration mishaps.[2][3]
Meanwhile, you could also face liability risks if you invite friends or relatives over for holiday gatherings. For example, a guest who gets hurt by slipping on an icy driveway or taking a chunk of ice to the face amid a friendly snowball fight could sue you on account of their injury. Similarly, if you plan to prepare a meal for your extended family’s holiday dinner, you could be held liable if a visitor gets sick after eating your cooking.
Renters
Renters generally face the same property damage and liability risks as homeowners during the winter. While a renter isn’t personally responsible for damage to the structure of the home they rent, they could still have to pay to replace damaged items or cover temporary living arrangements if a covered peril — like a winter storm — causes so much damage that their house or apartment becomes unsafe to live in.
Car Owners
Fatal car accidents involving pedestrians are particularly common in late fall and early winter, with 30% of all pedestrian deaths occurring from October to December in 2023.[5] Additionally, a 2017 analysis found that New Year’s Day is the second-deadliest day of the year for drivers on average — only behind Independence Day — likely due to hazards like icy roads and drunk drivers.[6][7]
Business Owners
Some of the most pressing issues business owners frequently face during the winter months include the following:[8]
- Supply chain issues and other business disruptions caused by inclement weather
- Power outages
- Employee accidents and illnesses
- Slip-and-fall lawsuits filed by customers injured on icy sidewalks or parking lots
- Frozen pipes and equipment
- Roof collapse and other types of snow or ice damage to warehouses and other buildings
What Types of Insurance Do I Need To Cover Winter Weather?
In the upcoming sections, you’ll learn about the main types of insurance policies that can cover the risks noted in the previous sections.
Homeowners
A standard homeowners insurance policy includes multiple coverage types that can help after a winter disaster. For example, dwelling coverage and other structures coverage insure your home and standalone structures on your property against any source of damage that isn’t listed as an exclusion in your insurance policy. Meanwhile, personal property coverage insures your furniture, appliances and other belongings against the perils listed in the table below.
|
Fire or lightning |
|
|
Windstorm or hail |
Volcanic eruptions |
|
Explosion |
Falling objects |
|
Riot or civil commotion |
Weight of ice, sleet or snow |
|
Damage by aircraft |
Water/steam discharge from home systems and appliances |
|
Damage by vehicle |
Sudden/accidental tearing, cracking, burning or bulging of home systems |
|
Smoke |
Freezing of home systems |
|
Vandalism or malicious mischief |
Sudden/accidental power surges |
Your homeowners policy also includes medical payments coverage to take care of hospital expenses after someone incurs a minor injury or illness on your property and personal liability coverage to handle larger medical bills, property repair costs for others and legal fees in case a holiday liability claim escalates into a lawsuit.
Finally, standard home insurance policies come with loss of use coverage. This coverage type guarantees you won’t be left out in the cold this winter by covering additional living expenses — such as restaurant meals, laundromat costs and hotel stays — that you would otherwise be on the hook for after a covered peril renders your home uninhabitable.

Renters
Much like homeowners insurance, renters insurance generally includes personal property, medical payments, personal liability and loss of use coverage. However, renters insurance policies do not include dwelling or other structures coverage because the structure of your rental unit and other freestanding structures on the property you rent should be covered by your landlord’s insurance instead.
Auto
In every state besides New Hampshire, drivers are required by law to carry liability car insurance.[9] This coverage type can pay for vehicle repairs or replacements and medical treatments for the other driver and their passengers if you are determined to be at fault for a car accident that occurs on an icy road.
Other car insurance coverage types that are required in some states — and worth considering even when optional — include collision insurance for your own car repairs after a crash you cause, medical payments coverage or personal injury protection for your own medical bills and comprehensive insurance for damage to your vehicle from a noncollision source, such as a snow-laden tree that falls on your car.
Although it is never required, you may also want to purchase roadside assistance coverage. Available as either a car insurance add-on or a standalone plan, roadside assistance can cover towing, jumpstarts, fuel delivery, tire changes and more if you end up stranded on the side of the road due to an accident or mechanical breakdown.
Commercial
Numerous components of a commercial insurance policy could come in handy throughout the winter. For example, commercial property insurance can cover damage to or the loss of your commercial items and the building they are stored in. In addition, general liability insurance can cover property repairs, hospital bills or legal expenses related to a liability claim against your business.
Another crucial coverage type included in many business owners policies is business interruption coverage, which takes care of expenses that come up when a covered peril temporarily prevents your business from operating as usual. For example, it could make up for lost revenue if a sudden snowstorm unexpectedly delays the shipment of inventory to your retail store.
Of course, your commercial insurance policy also needs to include workers’ compensation insurance, which can cover medical or rehabilitation costs and reimbursement for lost wages if an employee experiences an injury or illness on the job. Keep in mind that workers’ compensation insurance is required by law for most businesses in most states.[10]
Additional Coverage Options
It’s important to maintain health insurance heading into the winter months in case you experience a health problem that could otherwise lead to significant medical debt. The Health Insurance Marketplace open enrollment period lasts from Nov. 1 to Jan. 15 in most states, meaning the majority of Americans can freely sign up for Marketplace coverage around the beginning of winter.[11]
Along with covering physical injuries you may incur due to icy weather, all health plans offered through the Marketplace are required to cover mental health services.[12] As a result, a Marketplace health insurance plan may prove invaluable if you experience seasonal depression — which is most common in the fall and winter.[13]
Meanwhile, you should also note that flood damage isn’t covered by a typical homeowners, renters or commercial insurance policy, so you may need to buy extra flood insurance coverage if you live in an area that is prone to flooding in the winter, such as a coastal region in the Northeastern United States.[14]
How To File a Winter Insurance Claim
Take these steps to file an insurance claim amid cold weather this winter:
- Call 911 so paramedics can provide medical care and responding officers can fill out a police report, if necessary.
- Document the damage, and collect relevant evidence to support your claim.
- Contact your insurance carrier to initiate the claims process.
- Provide all of the evidence and information that your insurance company may need to assess your claim.
- Once your claim has been approved, use the insurance payout to cover property repairs or replacements, medical bills or whatever other loss needs to be addressed.

- Insurance quotes /
- Winter Insurance
Dylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health and life insurance under his belt. He has over nine years of experience writing for online publications, primarily about gaming and esports. In the process, he has become an expert in search engine optimization, news reporting, feature writing and copy editing.


Get a Free Insurance Quote Online Now.
More on Insurance
Get a Free Insurance Quote.
Compare rates from dozens of companies in less than 3 minutes.