

Do I Need Mechanical Breakdown Insurance for My Car?
 Written by Dylan Tate Dylan TateDylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health a... Read more |  Edited by Richard Murphy Richard MurphyRichard Murphy manages content on SmartFinancial's website. With a strong background in content strategy and copywriting... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
Mechanical breakdown insurance (MBI) is an optional type of car insurance that covers repairs to your vehicle if it experiences a mechanical or electrical failure that isn’t covered by your standard auto insurance policy. MBI isn’t always necessary, but it may be worth considering if you plan on keeping your car for a long time.
Keep reading to learn what MBI does and doesn’t cover — and whether it may make sense for your vehicle.
|
Key Takeaways
|
On This Page

What Is Mechanical Breakdown Insurance?
How Does Mechanical Breakdown Insurance Work?
What Does Mechanical Breakdown Insurance Cover?
What’s the Difference Between MBI and Car Warranties?
How Much Does Mechanical Breakdown Insurance Cost?
How To Get Mechanical Breakdown Insurance for My Car?
Things To Consider When Purchasing Mechanical Breakdown Insurance
FAQs

What Is Mechanical Breakdown Insurance?
Mechanical breakdown insurance — also known as car repair insurance — is a car insurance add-on that can pay to repair sudden and unexpected damage to your car’s parts and systems. Unlike physical damage insurance, it generally applies if your car breaks down due to an internal failure rather than an external accident or peril.
You may only be able to purchase and maintain mechanical breakdown coverage for a limited window of time. For example, GEICO only sells MBI to first-time buyers whose cars are less than 15 months old and have less than 15,000 miles on the odometer. After that, coverage can only be renewed for up to seven years or 100,000 miles, whichever comes first.[1]
How Does Mechanical Breakdown Insurance Work?
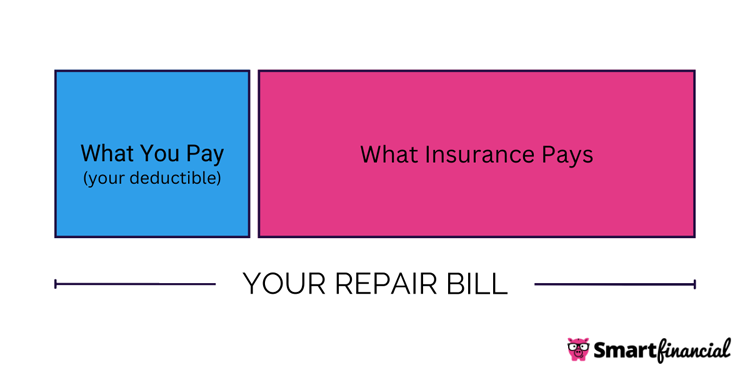
Like many other types of car insurance, mechanical breakdown insurance comes with a deductible, which is the minimum amount of money you agree to pay toward covered losses before your insurance provider starts chipping in. For example, MBI claims through GEICO require a $250 deductible — so if you need $10,000 to replace your engine after it breaks down, you may qualify for a $9,750 insurance payout.[1]
There is some overlap between MBI and a car warranty, though warranties may only cover defective parts and other manufacturing errors.[1] When you buy a new car, it will generally be covered by a comprehensive factory warranty for up to three years or 36,000 miles, whichever comes first. Certain components — like your powertrain — may be covered for longer.[2]
If you intend to keep your new car for only a few years, you may want to forgo mechanical breakdown coverage since your car should be covered by its manufacturer’s warranties for as long as you have it. However, MBI may be a cost-effective alternative to an extended warranty after your car’s free warranties have expired — potentially making it a worthwhile investment if you expect to drive the same vehicle for several years.
Is Mechanical Breakdown Insurance Required?
Mechanical breakdown car insurance is not required by law in the District of Columbia or any state. Furthermore, MBI is not typically required by auto lenders or leasing companies. As a result, you can generally expect car repair insurance coverage to be optional for you, regardless of your circumstances.
What Does Mechanical Breakdown Insurance Cover?
Mechanical breakdown insurance can cover the costs of parts and labor if your car experiences unforeseen damage that isn’t caused by an accident or other external source. This can include breakdowns due to design flaws, short circuits and other internal malfunctions. Car parts that may be covered by MBI include the following:
- Engine, transmission and other powertrain components
- Fuel system
- Exhaust system
- Brakes
- Air conditioning system
- Electrical system
- Computer and other digital components
- Steering system
- Suspension system
What Isn’t Covered by MBI?
MBI doesn’t cover damage to your vehicle that is already covered by a full coverage car insurance policy. For example, MBI won’t pay for repairs if you crash into a tree because this would be covered by your collision insurance instead. Likewise, it doesn’t cover losses stemming from fire or theft since comprehensive insurance already accounts for these perils.
Similarly, your car repair insurance won’t cover the costs of towing after your car breaks down, so you will instead need to purchase roadside assistance to receive coverage for this expense and other benefits when you are stranded on the side of the road. In addition, your mechanical breakdown auto insurance policy won’t cover routine maintenance costs.[1]
Finally, MBI doesn’t cover intentional damage or predictable wear and tear, nor does it cover losses that result from neglect or poor upkeep, such as corrosion. In fact, if you fail to adequately maintain your vehicle, your insurance company may deny any claims you file on your mechanical breakdown insurance policy.[3]
What’s the Difference Between MBI and Car Warranties?
The main differences between MBI and an extended warranty include how you obtain and pay for them, how much coverage they provide and where they allow you to get your car fixed after a breakdown. See the following table for a more detailed overview of the major differences.
|
Mechanical Breakdown Insurance |
Extended Car Warranty |
|
|---|---|---|
|
Supplier |
Insurance companies, banks and credit unions[4] |
Car dealerships, manufacturers and other third-party companies[5] |
|
Payment Schedule |
Monthly or annual payments |
Full lump-sum payment up front or an initial down payment followed by monthly payments[3][6] |
|
Pricing |
Lower premiums ($30 to $120 per year) with higher deductibles ($100 to $500)[4] |
Higher premiums ($0 to $350 up front plus $360 to $1,800 per year) with lower deductibles ($50 to $250)[3][6] |
|
Eligible Repair Shops |
Any repair facility[7] |
Only authorized repair shops or the dealership that sold you the car[5] |
Generally, mechanical breakdown insurance is a better value than an extended warranty because it is significantly cheaper and offers more flexibility whenever you need a repair. However, an extended car warranty could be a useful alternative if you have an older vehicle that is not eligible for MBI — for instance, some providers allow you to purchase an extended warranty for a car that’s up to seven years old or has driven up to 100,000 miles.[3]
Keep in mind that, since you must purchase MBI while your car is fairly new, it may be somewhat redundant with your car’s factory warranties when you first obtain it. Nevertheless, it can fill in certain gaps in your warranties — covering sudden breakdowns that can’t be traced to a manufacturing defect, for example — and its value during your car’s later years may make it worth the temporary overlap.
How Much Does Mechanical Breakdown Insurance Cost?
Annual premiums for mechanical breakdown coverage may range from as low as $30 to as high as $120. Factors that can impact the amount you have to pay for coverage include the age and condition of your vehicle, the level of coverage you choose, your deductible, your claims history and your car’s mileage.[4]
How To Get Mechanical Breakdown Insurance for My Car?
When you shop for MBI, it’s a good idea to collect quotes from around three to five insurance carriers since different insurers use different underwriting methods — potentially resulting in different rates for the same coverage. The major challenge is that it can take a long time to contact insurance companies one by one to ask for quotes.
To simplify the process, consider shopping through SmartFinancial. You’ll only need to fill out a single online questionnaire to begin the process of comparing quotes. We can connect you with expert agents who can match you up with the best car insurance policy for your situation. Answer a few questions today, and you may receive free auto insurance quotes in as little as a few minutes.
Things To Consider When Purchasing Mechanical Breakdown Insurance
If you’re looking into mechanical breakdown insurance, the most important thing to consider is whether the amount of coverage provided is worth the cost. Pay close attention to policy exclusions and the deductible amount — these details will help you determine if an MBI policy meets your needs without creating an undue financial burden.
Additionally, you should plan for the future by figuring out how long you are allowed to renew your MBI policy and whether you can transfer your coverage to a different vehicle if your current car is totaled. Remember, mechanical breakdown insurance isn’t necessary for every driver — so weigh the potential long-term value before buying a policy.
- Insurance quotes /
- Auto /
- Mechanical Breakdown Insurance
Dylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health and life insurance under his belt. He has over nine years of experience writing for online publications, primarily about gaming and esports. In the process, he has become an expert in search engine optimization, news reporting, feature writing and copy editing.


Get a Free Auto Insurance Quote Online Now.
More on Auto Insurance

Looking for Auto Insurance?
Compare rates from dozens of companies in less than 3 minutes.