

What Is an HO-4 Insurance Policy?
 Written by Dylan Tate Dylan TateDylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health a... Read more |  Edited by Richard Murphy Richard MurphyRichard Murphy manages content on SmartFinancial's website. With a strong background in content strategy and copywriting... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
An HO-4 policy is a type of homeowners insurance that provides liability and additional living expenses coverage for people living in rented homes. It also includes property coverage that applies to personal belongings but not buildings or other structures. HO-4 renters insurance is not a legal requirement, but it is commonly required by landlords.
Continue reading to learn more about HO-4 insurance coverage, including the perils typically covered and the exclusions you should be aware of.
|
Key Takeaways
|


How Does an HO-4 Insurance Policy Work?
HO-4 insurance, also known as renters insurance, provides a financial safety net for someone who rents a house, apartment or condo in case a sudden peril damages their home or possessions or they are held responsible for another person’s injury or damage to their property. HO-4 policies generally cover your belongings at their actual cash value (ACV).
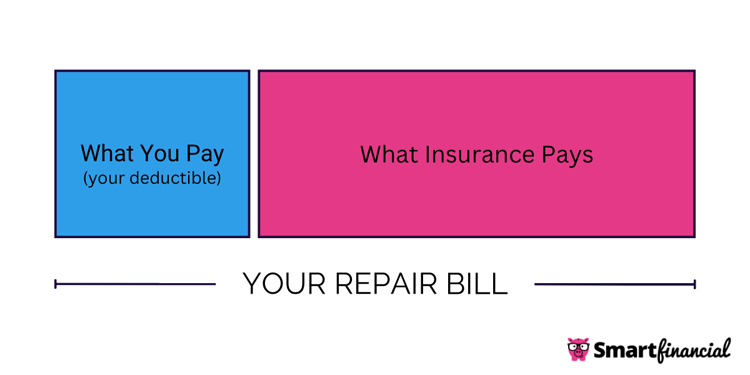
However, if you are willing to pay a higher premium — typically around 10% more — you can instead insure your property at its replacement cost value (RCV). This means your insurer will pay the cost to replace your lost items with similar ones after a covered loss — up to your policy’s coverage limit.[1] Keep in mind that claims related to damaged belongings always require you to make an out-of-pocket contribution known as a deductible.[2]
What Does an HO-4 Policy Cover?
A standard renters insurance policy includes the following four coverage types:
- Personal property: Personal property insurance can pay to repair or replace personal items — such as furniture, clothing and electronics — if they are damaged or destroyed by a covered peril. HO-4 policies typically include off-premises coverage for claims involving belongings outside of your home, though the coverage limit for off-premises claims may only be 10% of the overall personal property coverage limit.[1]
- Loss of use: If you need to temporarily move out because a covered peril has left your home uninhabitable or you are otherwise unable to return home, loss of use coverage can take care of additional living expenses, like restaurant meals, hotel stays and laundromat costs.
- Personal liability: Your personal liability insurance can cover medical expenses and property repairs or replacements if you are held responsible for someone’s injury or damage to their property. In addition, it can cover legal expenses if you are sued over a bodily injury or property damage claim.
- Medical payments: Similarly, medical payments coverage can pay hospital bills if someone is injured on your property — even if you aren’t held liable for the injury. However, medical payments coverage generally comes with a lower coverage limit than personal liability insurance and doesn’t cover legal fees, so it’s best used as a deterrent to prevent a minor bodily injury claim from escalating into a costly lawsuit.

In general, HO-4 policies insure your belongings only against named perils that are specifically listed in the policy. Covered causes of damage typically include the following:
|
Vandalism or malicious mischief |
|
|
Explosion |
Volcanic eruption |
|
Riot or civil commotion |
Falling objects |
|
Damage by aircraft |
Weight of ice, sleet or snow |
|
Damage by vehicle |
Freezing of home systems |
|
Smoke |
Sudden/accidental power surges |
|
Sudden/accidental tearing, cracking, burning or bulging of home systems |
Water/steam discharge from home systems and appliances |
What Isn't Covered?
Your HO-4 insurance policy won’t cover anything that should instead be covered by a separate insurance policy or is normally excluded from homeowners insurance coverage. These are some of the most common exclusions that renters ought to keep in mind:
- Buildings: Unlike a typical home insurance policy, renters insurance does not include dwelling coverage or other structures coverage because the physical structure of your home and other freestanding structures on your rental property — like sheds and fences — should instead be covered by your landlord’s insurance policy.
- Roommates: Depending on your state and insurance company, your renters insurance policy may not extend coverage to your roommate unless you are married or related to them.[3]
- Floods and earthquakes: While renters insurance provides coverage for most kinds of natural disasters, floods and earthquakes are often excluded. As a result, you may need to buy separate flood insurance and earthquake insurance to protect your personal property from these perils.
- Gradual damage: The main purpose of insurance is to protect you from financial losses due to sudden and unexpected perils, so your insurer may not cover more progressive sources of damage, like poor maintenance, wear and tear, infestations or mold.
- Certain dog bites: Personal liability insurance usually covers claims related to dog bites, but your policy could exclude coverage for dog breeds that have a reputation for being aggressive, such as Rottweilers and pit bulls.
- Your medical expenses: Although HO-4 insurance can cover your guests’ medical bills in certain cases, it won’t cover medical treatments for you or your housemates. Instead, you will need to purchase health insurance to cover your own medical care.
How Much Does an HO-4 Policy Cost?
In 2022, the average cost of renters insurance was $171 per year — far below the $1,569 annual average that homeowners paid for home insurance.[4] Of course, premiums can vary based on factors like the insurance company you buy your policy from, the coverage limits and deductibles you choose, where you live and whether you are eligible for any discounts.
Do I Need an HO-4 Policy?
Renters insurance is not required by law in any state. That said, it’s likely that your landlord will require you to buy an HO-4 policy before renting out their property to you. Even if it’s not mandatory for you, purchasing renters coverage is still a wise investment to protect yourself in case a sudden peril causes significant damage to your property or you are sued because of an unexpected liability claim.
How Much Renters Insurance Do I Need?
You should generally maintain enough personal property insurance to replace all of your most important belongings in case they are destroyed by a significant peril, like a house fire. To get a precise estimate of the value of your belongings to help you decide how much personal property coverage to purchase, consider making a home inventory.[1]
Meanwhile, the loss of use coverage limit for an HO-4 policy may be set at a flat amount, or it may be based on your personal property coverage limit. For example, Lemonade usually sets the loss of use coverage limit for renters policies at 30% of the personal property coverage limit, but policyholders have the option to raise the limit to as much as $200,000.[5]
Finally, your HO-4 insurance policy should come with at least $100,000 worth of personal liability coverage. For more comprehensive protection, consider raising your liability limit to $300,000 or higher. Additionally, you should have the option to purchase between $1,000 and $5,000 worth of no-fault medical payments coverage.[1]
How Do I Get an HO-4 Policy?
You should obtain quotes from at least three to five renters insurance companies so you can compare rates and see which carrier can offer you the best deal. Unfortunately, it can be burdensome to individually reach out to insurers to provide them with information like your address, the number of people living in your home and the approximate value of your belongings.
However, you can make the process much easier by using an insurance marketplace, like SmartFinancial. We can collect information about your coverage needs and budget through a simple online questionnaire and then share that information with an insurance agent in your area. To get started on comparing free renters insurance quotes, click here and enter your ZIP code.
- Insurance quotes /
- Home /
- What Is Ho4 Insurance Policy
Dylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health and life insurance under his belt. He has over nine years of experience writing for online publications, primarily about gaming and esports. In the process, he has become an expert in search engine optimization, news reporting, feature writing and copy editing.


Get a Free Home Insurance Quote Online Now.
More on Home Insurance

Looking for Home Insurance?
Compare rates from dozens of companies in less than 3 minutes.