

What Type of Insurance Do I Need To Buy a Used Car?
 Written by Dylan Tate Dylan TateDylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health a... Read more |  Edited by Dan Marticio Dan MarticioDan Marticio is the content manager at SmartFinancial and has written 150+ articles across multiple insurance verticals.... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
At the very least, you will need liability insurance and any other car insurance coverage types required by law in your state to purchase and drive a used car. If you take out a loan to pay for your vehicle, then your used car insurance policy will likely have to include comprehensive and collision coverage as well.
Read below to learn about how to get insurance for used cars, how much you can expect to spend on car insurance for a used car and more.
|
Key Takeaways
|


What Is Used Car Insurance?
Used car insurance simply refers to a standard auto insurance policy that covers a used vehicle, as a used car does not necessarily need a different type of insurance policy than a newer car. That said, auto insurance for used cars may be cheaper than coverage for newer vehicles, and it may require fewer coverage types as well.
Do I Need Car Insurance Before Buying a Used Car?
In most cases, you won’t be able to purchase a new or used car unless you have an insurance policy in place to cover it. If you already have car insurance, you should be able to add a newly purchased used vehicle to your current policy. Your insurer may even offer a grace period of up to one month, meaning your car will be automatically covered by your existing policy for a limited time before you officially add it to the policy.[1]
Keep in mind that auto insurance is required by law in every state besides New Hampshire.[2] As a result, even if you buy your used car from a dealership that doesn’t ask you to show proof of insurance, it is still against the law for you to drive your used car without adequate insurance coverage.
What Does Used Car Insurance Cover?
Car insurance policies are required to include both bodily injury and property damage liability coverage in all states except for Florida, where drivers can go without bodily injury liability coverage.[3] This means your used car auto insurance policy should cover someone else’s repair bills if you crash into their car or other property, along with medical bills, lost wages, funeral expenses and legal costs as necessary if you injure or kill someone in a car accident.
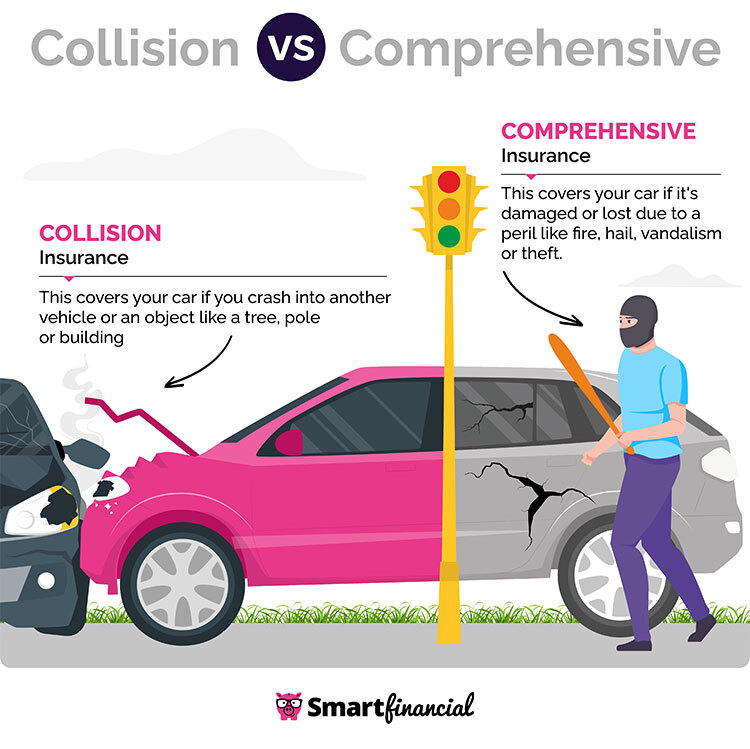
In addition, if you finance your used car purchase rather than paying for it in full up front, you will likely be required by your lender to maintain the two physical damage insurance coverage types: comprehensive and collision coverage. Collision insurance covers your vehicle after a crash that you are responsible for, while comprehensive insurance pays to repair or replace your car if you experience a loss from a non-collision source, like a falling tree, a deer strike or theft.
Depending on where you live, you may also be required by law to carry coverage types like these for your used vehicle:
|
Coverage |
Description |
|---|---|
|
Uninsured motorist coverage (UM) |
Covers your medical expenses and car repairs if you are hit by someone who doesn’t have car insurance or if you can’t identify the driver after a hit-and-run |
|
Underinsured motorist coverage (UIM) |
Covers leftover costs if you are struck by a driver who doesn’t have enough insurance to fully cover your medical expenses or car repairs |
|
Personal injury protection (PIP) |
Covers your medical bills, lost wages and funeral expenses if you are at fault for the accident |
|
Medical payments coverage (Medpay) |
Covers your medical bills and funeral expenses if you are at fault for the accident, but doesn’t cover lost wages |
|
Property protection insurance (PPI) |
Covers someone else’s property repairs if you crash into their parked car or other non-vehicle property (applies only in Michigan)[4] |
How Much Does Used Car Insurance Cost?
The average cost of full coverage car insurance across all vehicles is over $2,000 per year, but generally, it is cheaper to insure a used car than a new vehicle, so you may see used car premiums fall below this figure.[5] This is typically due to cars depreciating in value over time and, as a result, costing less for insurance companies to replace if totaled in a car accident.
Factors That Affect Used Car Insurance Rates
Some of the biggest factors impacting how much you have to pay for car insurance for used cars include the following:[6]
- Driving record: Your personal driving record is one of the most important factors in determining car insurance rates. Drivers with little driving experience or multiple car accidents and other driving infractions in their driving history can expect to pay much more than experienced drivers with clean driving records.
- Vehicle use: Insurance companies take into account how much you drive when calculating your risk of getting into an accident. For example, someone with a long commute to work can generally expect to pay more than someone who works from home and only drives occasionally.
- Location: Numerous location-dependent factors can impact car insurance prices, such as crime rates, accident prevalence, weather patterns, cost of living and more.
- Age: Since older drivers tend to be more experienced and less likely to get into car accidents, they usually pay less for auto coverage than drivers under the age of 25.
- Sex: Men could have to pay more than women for the same coverage, since men are statistically more likely to cause major collisions or commit serious moving violations.
- Vehicle: The cost of your vehicle plays a significant role in determining car insurance premiums, as more valuable cars are costlier to replace and therefore costlier to insure. Your insurance carrier will likely also consider your car’s safety features, average repair costs and exposure to theft, among other things.
- Credit score: While it is not legal to do so in every state, auto insurance companies in many states set rates based on a credit-based insurance score that predicts your likelihood of filing an auto insurance claim.
- Policy details: Various insurance policy details will factor into the amount you have to pay for coverage, including your policy’s coverage types, coverage limits and deductibles.
What Are the Differences Between New and Used Car Insurance?
In general, the biggest differences between car insurance policies for new cars and used cars are their premiums and the coverage types they include. Although auto insurance tends to be cheaper for used cars because of their lower value, it’s worth noting that used cars may lack the advanced safety features that newer cars possess, so you may not qualify for certain discounts for your used vehicle like you might for a newer vehicle.
Typically, it’s recommended that you drop these coverage types if their combined premium is greater than 10% of the value of your car.[7] For example, if your vehicle is worth less than $4,000, it may not be worth paying more than $400 per year for physical damage coverage.
How To Get the Best Deal on Used Car Insurance
You can find the best deal on auto insurance for your used car by shopping around, which involves comparing quotes from around three to five different car insurance companies. This can, of course, become a hassle if you try to contact multiple different insurers one by one to give them information about your car, location and driving record.
Enter SmartFinancial. Our technology platform enables you to be connected with insurance agents who are experts at helping people find the best car insurance policies for their circumstances, and all you have to do to get started is fill out a simple questionnaire. Click here to begin your questionnaire and start comparing car insurance quotes for free.
- Insurance quotes /
- Auto /
- Used Car Insurance
Dylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health and life insurance under his belt. He has over nine years of experience writing for online publications, primarily about gaming and esports. In the process, he has become an expert in search engine optimization, news reporting, feature writing and copy editing.


Get a Free Auto Insurance Quote Online Now.
More on Auto Insurance

Looking for Auto Insurance?
Compare rates from dozens of companies in less than 3 minutes.