
20 Weird Types of Insurance You Never Knew Existed
 Written by Preston Micalizio Preston MicalizioPreston Micalizio writes insurance content for SmartFinancial. He brings three years of professional experience writing ... Read more |  Edited by Richard Murphy Richard MurphyRichard Murphy manages content on SmartFinancial's website. With a strong background in content strategy and copywriting... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
Weird types of insurance often include unique coverages for uncommon events, but some, like alien abduction insurance, can seem really out of this world. While some oddball insurance types may seem silly or unnecessary, they show you can get coverage for nearly any specific need if you’re willing and able to pay the attached premium.
For those interested in learning about some of the strangest insurance types, read on to learn more about several unique types of insurance and how to get them.
|
Key Takeaways
|


What Is Weird Insurance?
Weird insurance is coverage you might get only for very specific scenarios or novel events. Insurance costs tend to be correlated with the risk of making a payout, so some policies for outrageous or extremely unlikely events may be very affordable, such as roughly $20 for a lifetime policy on alien abduction coverage, making them a common novelty gimmick gift or personal accolade.[1]
Other forms of weird insurance may have been available previously for specific events, but are no longer offered for various reasons. However, some weird types of insurance may not exist at all and are instead incorporated into more mainstream insurance. For example, coverage against asteroids doesn’t have its own insurance policy but is actually covered by homeowners or comprehensive car insurance.[2][3]
What Are Weird Types of Insurance?
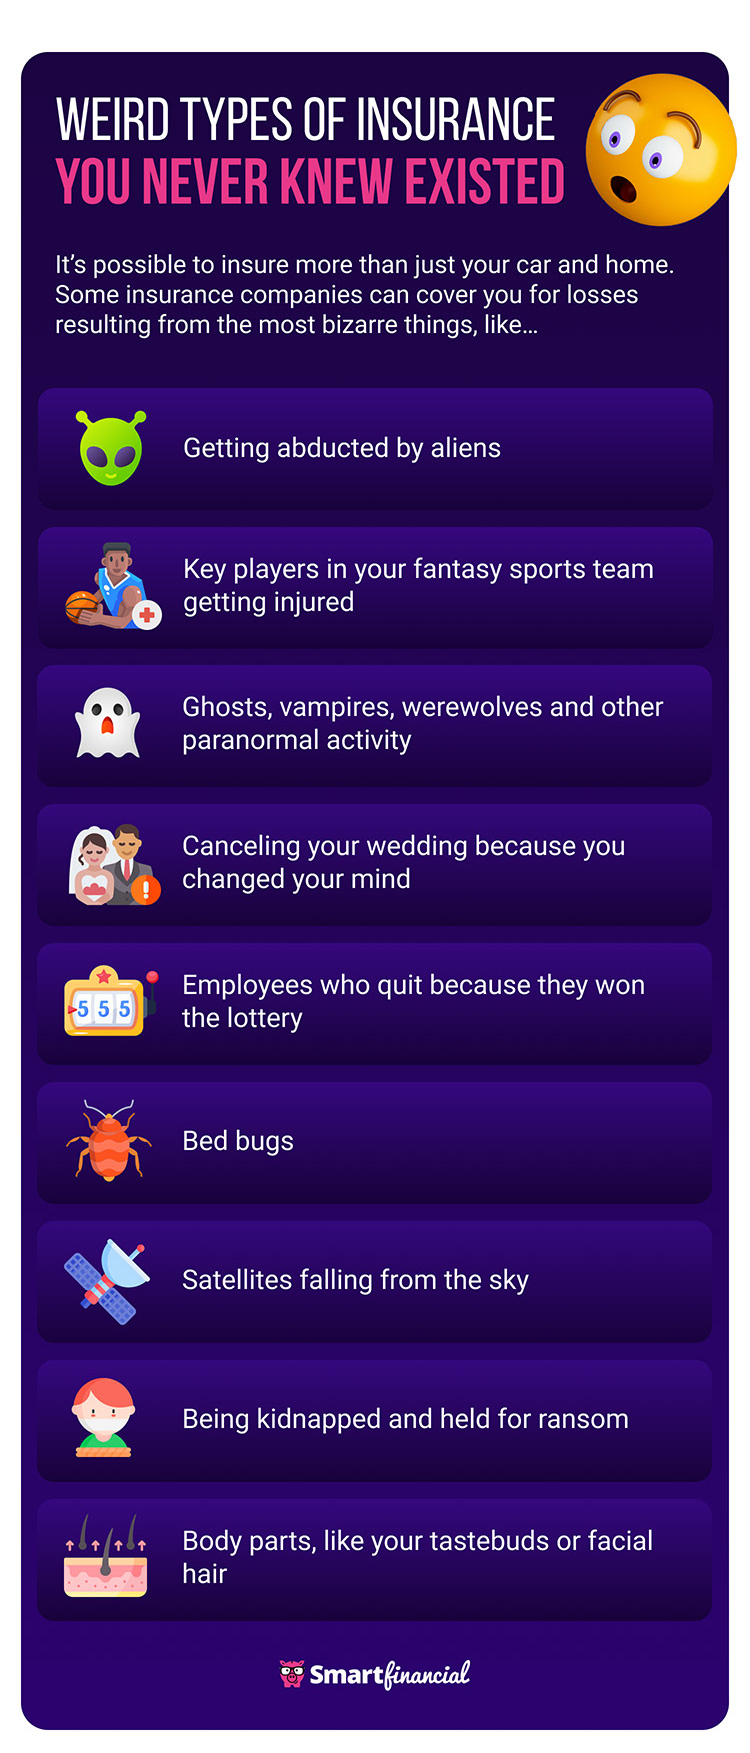
Below, we’ll cover several unusual or weird types of insurance, including whether they’re real, only for specialized scenarios, novelties, once historically offered or policies too bizarre to be believed.
|
Weird insurance |
Is it a real policy? |
Who’s it for? |
Typical coverage |
|---|---|---|---|
| Alien abduction insurance | Novelty | Potential victims of an alien abduction | Medical and psychiatric care costs and financial payout |
| Body part insurance | Novelty | Individuals who rely on specific physical attributes | Financial payout if the body part is damaged or lost |
| Fantasy football insurance | Historically offered | Those with a fantasy football league concerned about player injuries | Payout when a player on your fantasy team gets injured |
| Asteroid insurance | Not real (covered by home and comprehensive auto | Those concerned about falling asteroid damage | Would cover losses from falling asteroids and space objects |
| Paranormal insurance | Novelty | Victims of attacks by paranormal forces | Injury, death or trauma from a paranormal encounter |
| Key person insurance | Real | Businesses with essential employees or executives | Costs associated with replacing a key person, offsetting lost revenue or closing the business |
| Change of heart insurance | Specialty | Engaged couples | Nonrefundable costs when a wedding is canceled for a reason within the couple’s control |
| Collectibles insurance | Real | People with expensive collectible items | Losses or damage to the collection |
| Lottery insurance | Specialty | Lottery ticket buyers and their employers | Covers losing lotto ticket costs as well as the costs of covering a winning employee who quits |
| Livestock insurance | Real | Farmers, ranchers and others in animal agriculture | Losses of livestock for various named scenarios |
| Bed bug insurance | Specialty | Homeowners, renters and landlords | The cost of damages due to bed bugs |
| Moving insurance | Real | People moving their personal belongings | Loss of damage to belongings during a move |
| Thailand riot insurance | Historically offered | Those visiting Thailand between 2010 and 2011 | Injuries and damages due to riots in Thailand |
| Kidnap and ransom insurance | Specialty | Organizations and their families | Ransom costs, losses of ransoms during transfers and other potential expenses |
| Bicycle insurance | Real | Bike and e-bike owners | Covered losses of your bike, alongside damages or injuries you may be liable for causing while riding it |
| Food truck insurance | Specialty | Food truck owners | Various business losses or liabilities related to running a food truck |
| Haunted house insurance | Specialty | Haunted house and seasonal event operators | Liability and damages related to operating a seasonal Halloween event |
| Party guest insurance | Real | Hosts of special events | Damages and injuries you’re responsible for while hosting the event |
| Spaceship insurance | Specialty | Satellite owners, launch providers and governments | Damages and liabilities for spacecraft and launch vehicles |
| Contest and prize insurance | Specialty | Sweepstakes and promotional event organizers | Covers the cost of a winning prize |
1. Alien Abduction Insurance
If you fear an invasion by extraterrestrial beings, alien abduction insurance has you covered. Alien abduction policies can include medical and psychiatric care to deal with the fallout of having been taken by aliens, as well as a potentially large financial sum.
The most notable carrier offering this unique insurance is the Saint Lawrence Agency in Florida, which has sold thousands of UFO abduction insurance policies since 1987. The catch is that while these policyholders earn a $10 million payout, they receive only $1 a year for 10 million years or until they die.[1]
2. Body Part Insurance
Body part insurance, or celebrity insurance, protects individuals whose careers depend heavily on specific physical attributes from financial loss, ranging from noses to voices and facial hair. This type of insurance is crucial for individuals like athletes, musicians, models and actors whose earning potential could be jeopardized by an injury or disfigurement to essential body parts. For example, KISS frontman Gene Simmons insured his famous tongue for $1 million.[4]
3. Fantasy Sports Insurance
Fantasy sports insurance offers financial protection to fantasy sports league participants if a key player on their team gets injured, which could derail their chances of winning. Your premium would be based on the player’s injury history, so players with more frequent injuries would cost more to insure. While fantasy sports insurance policies emerged around 2014, most insurers haven’t offered them since 2021.[5]
4. Asteroid Insurance
Homeowners looking to protect their property from falling meteoroids with asteroid insurance are out of luck, as this insurance is purely fictional. However, you don’t have to worry about the threat of celestial bodies crashing into your home without protection – your standard homeowners insurance will typically protect you from perils like falling objects, which include falling satellites, meteoroids and comets.[2]
Car owners can also benefit from comprehensive car insurance to protect themselves from vehicle damage caused by falling asteroids and other objects from space.[3]
5. Paranormal Insurance
Paranormal insurance covers the bizarre and eerie domain of supernatural occurrences with financial protection against ghostly hauntings, vampire bites or werewolf attacks and other occurrences beyond the scope of normal scientific understanding. While it may be difficult to prove, this novelty “Spooksafe” policy is offered by some insurers to cover policyholders who are injured or killed due to paranormal encounters.[6]
6. Key Person Insurance
Key person insurance safeguards a business against the financial repercussions that may arise from the death or incapacitation of a key individual within the organization. While somewhat morbid, this very real form of business insurance covers a "key person" in an organization – usually someone whose knowledge, creativity, leadership or business acumen is deemed crucial to the company's financial health and operational continuity. The business takes out this insurance policy on the life or health of that vital individual, with the business listed as the beneficiary.
Key person coverage typically includes life insurance and potentially disability insurance, ensuring the company receives a financial payout if the key person dies or becomes unable to work. Funds from a key person insurance policy can cover temporary staffing costs, help recruit a replacement, offset lost revenue or ease the transition if the business must be sold or closed.
7. Change of Heart Insurance
Change of heart coverage is one of those odd insurance policies that provides financial protection if a wedding is called off because one party gets cold feet. This type of insurance covers expenses such as deposits for venues, caterers, photographers and other vendors, which often have nonrefundable clauses.[7]
Most insurers that provide wedding insurance will only cover wedding cancellations outside your control, such as a major tornado that strikes the area or a sudden death in the family that forces a date change. However, some insurers offer “change of heart” wedding coverage that includes cancellations within your control, such as if you and your betrothed have a qualifying breakup. These policies could let you recoup up to 75% of your nonrefundable wedding costs, making them enticing for anyone with second thoughts at the altar.[7]
8. Collectibles Insurance
Collectibles insurance protects the financial investment collectors have made in acquiring unique, rare or valuable items. Whether it's stamps, coins, vintage toys, sports memorabilia or art, a collection can represent not only a significant monetary investment but also an emotional one.
This type of insurance covers risks such as theft, damage or loss, ensuring the collector can be compensated for the items' monetary value in such events. Unlike standard homeowners or renters insurance, collectibles insurance often provides broader coverage with higher limits to reflect the items' true value.
9. Lottery Insurance
Lottery insurance can help cover the costs of your lottery tickets if you play and don’t win. Employers can also get coverage with employee lottery insurance, which is designed to protect businesses from the potential financial hardship if one or more employees quit abruptly after winning the lottery.[8] For some businesses, this somewhat novel insurance policy can be a big cost saver, since employee turnover can cost 50% to 200% of an employee's annual salary, with higher losses if the employee was a key player in the business’s operations.[9]
10. Livestock Insurance
Livestock insurance is a crucial financial safeguard for farmers, ranchers and others involved in the animal agriculture sector against losses related to their livestock. This insurance can cover many scenarios, including accidental livestock shootings, loading and unloading accidents, wild animal attacks, fires, floods and other named perils.[10]
11. Bed Bug Insurance
Bed bug insurance covers the costs of damages caused by the insect pests. For homeowners or renters, basic home insurance or renters insurance typically won't cover bed bug-related losses, but some insurers may offer bed bug coverage through an endorsement for an additional premium. And while landlords may not have to deal with the physical discomfort of bed bugs, they may have to deal with the financial fallout of having to get rid of them if their tenants complain, making bed bug coverage essential.[11]
12. Moving Insurance
Moving insurance protects your personal belongings during a relocation, whether it's a local move or a long-distance one. This insurance typically covers loss or damage to your belongings caused by accidents, mishandling, theft or other unforeseen events during the move, and moving companies usually offer it to their clients. While moving companies typically offer their own coverage, you can purchase additional moving insurance from third-party insurers.[12]
Moving insurance comes in different forms, including full value protection, where the moving company is liable for the replacement value of lost or damaged goods. This is typically the more expensive coverage. The other option is released value coverage, which covers items based on weight at a specified rate per pound, potentially 60 cents per pound.[13]
13. Thailand Riot Insurance
Thailand riot insurance was briefly available between 2010 and 2011 to safeguard tourists from financial loss due to injuries or delays caused by anti-government riots during their visit to Thailand.[14] This initiative, which included $10,000 in coverage for tourists injured due to rioting, aimed to boost tourism during periods of political unrest. It was part of broader tourism stimulus efforts by the Thai government, which extended the insurance coverage alongside a free tourist visa scheme to encourage tourist arrivals amid the challenging political climate.[15]
14. Kidnap and Ransom Insurance
Kidnap and ransom insurance was created to safeguard organizations and their families against the financial repercussions of incidents like kidnappings, extortion and unlawful detentions. This coverage generally encompasses the ransom amount, potential losses during its transfer and related unforeseen expenses resulting from such incidents.[16]
The risk of kidnapping isn't limited to specific industries or businesses. It can stem from personal vendettas, animosity toward the company or attempts to extract valuable company information.
15. Bicycle Insurance
Bicycle insurance is a tailored insurance product designed to cover damage or loss of the bicycle or e-bike, whether due to accidents, fire, vandalism or theft. It can also provide liability coverage if you cause injury to others or damage to their property while on your bike. Some policies may also cover personal accident benefits, providing financial assistance for medical treatment or rehabilitation if you suffer an injury while cycling.[17]
16. Food Truck Insurance
Food truck insurance is specialized coverage that addresses the unique nature of mobile eateries and the culinary operations carried out in a confined space. Some insurers may not offer a specific policy called “food truck insurance,” but instead sell a package of commercial insurance policies needed for food trucks to operate. These various coverage aspects help ensure holistic protection, often including but not limited to:[18]
- Business owner’s policy (BOP)
- Commercial auto insurance
- General liability insurance
- Workers’ compensation insurance
- Liquor liability insurance
17. Haunted House Insurance
Haunted house insurance is specialized coverage designed to address the risks of hosting Halloween events or operating haunted houses, spooky hayrides and corn mazes. While these events are in good fun, they also create unique liabilities, such as injuries from a malfunctioning smoke machine, an employee in costume accidentally injuring themselves in a trip-and-fall or property damage from a misplaced pyrotechnic effect.[19]
This insurance typically covers a variety of risks, including general liability for patron accidents, commercial auto for hayride tractors and commercial property coverage if rowdy patrons damage your business's physical assets. You may also qualify for workers' compensation, depending on your state's business requirements.[19]
18. Party Guest Insurance
Party guest insurance, otherwise called event liability coverage, shields hosts from costs linked to liability claims, such as accidental bodily harm, property destruction or claims related to personal and advertising harm (slander/libel) that might occur during the event. While these incidents are typically unintentional, they can be expensive without coverage.[20]
19. Spaceship Insurance
Before launching your next ship or satellite into orbit, you may want to consider spaceship insurance, also known as space insurance, which is designed to mitigate the financial risks associated with space exploration and utilization. Key coverage areas typically include:[21]
- Pre-launch insurance: Covers the risks associated with the assembly, testing and transportation of the spacecraft and its components before the launch.
- Launch insurance: Covers the launch phase, protecting against failures that could result in total loss or partial damage to the spacecraft.
- In-orbit insurance: Covers the operational phase once the spacecraft is in orbit, including coverage for collisions with other objects, system failures or other in-orbit perils.
- Liability insurance: Protects against claims arising from property damage or injury caused to third parties, either on the ground or in space, due to the spacecraft's operations.
20. Contest and Prize Insurance
Contest and prize insurance, or prize indemnity insurance, is a specialized insurance policy designed to cover the costs of prizes offered in contests, sweepstakes or promotional events conducted by companies or organizations. This insurance lets promoters offer large prizes to attract participants without risking out-of-pocket payouts.[22]
Of course, if the contest is particularly difficult to win, the business can bring in revenue without paying out the prize. However, if the rare event happens and someone wins a prize like a brand-new car, the insurance company would pay the cost.
Are These Policies Actually Real?
Nearly all of the above policies are either offered or have been offered in the past. Despite how weird some of the policies in the previous list may seem, insurers often offer coverage for unique or specialized scenarios.
Weird Types of Insurance at a Glance
Below is the essential information you should know about weird types of insurance:
- Weird types of insurance often cover unusual, unlikely or even impossible events.
- Specialty insurance is often available for specific scenarios beyond standard coverage, such as commercial property insurance for seasonal events or key person insurance for essential employees.
- Some insurers may offer novelty insurance policies, such as alien abduction insurance, which are rarely ever intended to provide legitimate coverage.
- Some weird insurance concepts, such as asteroid insurance, are actually covered by other standard insurance policies.
- You can check with a licensed insurance agent to find the best way to get weird and unusual types of insurance that standard insurers don't offer.
How To Buy Unusual or Specialty Insurance
Not all weird types of insurance are available from every insurer, and some of the more novel policies may only be available from a single underwriter. If you're looking to buy a particular type of insurance, it may be worth checking with a licensed insurance agent to see whether the coverage you want is available as part of a more common policy. For example, if you’re wary of falling satellites or meteors, you might want to consider purchasing homeowners insurance rather than looking for asteroid insurance.
- Insurance quotes /
- Weird Types Of Insurance
Preston Micalizio writes insurance content for SmartFinancial. He brings three years of professional experience writing in various industries, from higher education to e-commerce. He strives to engage with the audience, provide accurate reporting and make complex subjects easily digestible.


Get a Free Insurance Quote Online Now.
More on Insurance
Get a Free Insurance Quote.
Compare rates from dozens of companies in less than 3 minutes.