

Home Insurance and Robots: Is Smart Technology Covered?
 Written by Dylan Tate Dylan TateDylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health a... Read more |  Edited by Dan Marticio Dan MarticioDan Marticio is the content manager at SmartFinancial and has written 150+ articles across multiple insurance verticals.... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
Damage to and liability claims involving consumer robots, smart home devices and other technologies powered by artificial intelligence (AI) may be covered by a basic homeowners insurance policy. Nevertheless, your insurance policy may not have been specifically designed to cover an elaborate home robot, so it’s best to check with your insurance company before buying any kind of novel, advanced technology for your home.
Read on to learn more about home insurance and robots, along with what options may be available if you’re looking for more in-depth robotics insurance coverage.
|
Key Takeaways
|


What Types of Home Insurance Policies Cover Robots?
Drones, automated swimming pool cleaners or vacuums and other types of robotic technologies will most likely be covered by the personal property coverage portion of your home insurance policy, which broadly provides coverage for your belongings. Meanwhile, smart home systems that are directly built into the structure of your house may instead be covered by your dwelling insurance.
However, you may need to read over the details of your policy or contact your insurance agent to confirm whether your policy covers robots, as coverage for various types of technology can vary from insurer to insurer, and your insurance policy may not have been written with complex robots in mind.
For example, a broad form home insurance policy from State Farm generally covers household machines that are neither designed for travel on public roads nor subject to motor vehicle registration, but its exclusions for aircraft and other types of electronic devices and equipment could potentially be applied to drones and other types of robots.[1]
When Are Robots Covered by Home Insurance?
Robots that are covered by your personal property coverage should be insured on a named peril basis. This means that your insurance company will pay to repair or replace a covered robot only if it has been affected by one of the following 16 sources of damage:
|
Volcanic eruptions |
|
|
Explosion |
Falling objects |
|
Riot or civil commotion |
Weight of ice, sleet or snow |
|
Damage by aircraft |
Water/steam discharge from home systems and appliances |
|
Damage by vehicle |
Sudden/accidental tearing, cracking, burning or bulging of home systems |
|
Smoke |
Freezing of home systems |
|
Vandalism or malicious mischief |
Sudden/accidental power surges |
When Robots May Not Be Covered by Home Insurance
In general, your robots won’t be covered if they are damaged by any peril besides those listed in the previous table. Meanwhile, examples of common homeowners insurance exclusions that may apply even to built-in smart home devices covered by your dwelling insurance include the following:
|
Intentional losses |
|
|
Ground movements, like earthquakes |
Wear and tear or other types of gradual damage |
|
Infestations |
Nuclear hazards |
|
Acts of war |
|
|
Commercial property related to a home-based business |
Power failure and power surges that don’t originate on your property |
|
Government action |
Enforcement of local building codes |
Additionally, you should note that home insurance policies often set sublimits for valuable items, so these items may not be covered at their full replacement cost. While sublimits typically apply to things like jewelry and collectibles, your insurer could also set sublimits for your robots if they are particularly expensive.

Liability Coverage for Robots
A standard homeowners insurance policy includes personal liability coverage that may take care of robot-related liability claims. For example, your personal liability insurance may cover property repairs if your autonomous lawnmower crashes into your neighbor’s fence or medical bills if it runs over and injures a guest. In addition, personal liability coverage may pay for legal fees, judgments and settlements anytime someone sues you over a liability claim.
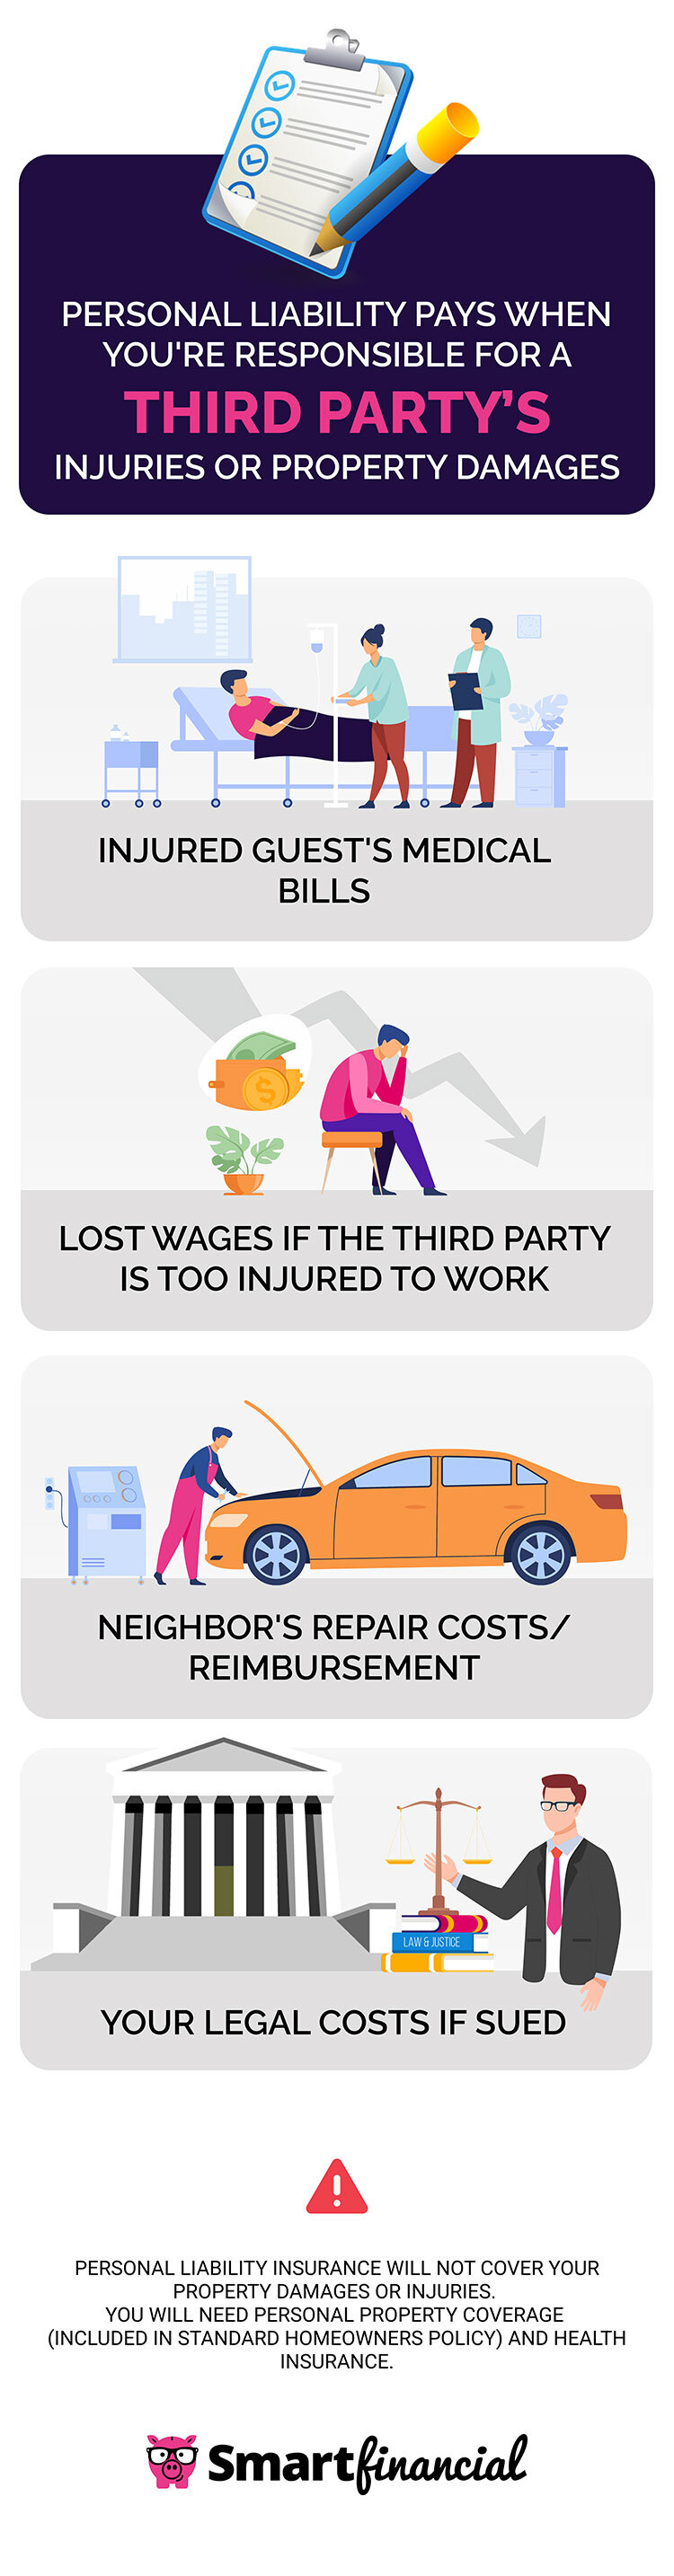
Most homeowners are advised to maintain between $300,000 and $500,000 in personal liability insurance, but you may want to purchase a policy with higher liability coverage limits or separate umbrella insurance if you have a robot with an increased risk of causing personal injury to someone.[2] Of course, you should double-check with your insurance company to make sure your policy doesn’t exclude liability coverage for emergent, high-tech machines.
Add-Ons and Specialized Coverage Options for Robots
In some cases, you may want to acquire additional coverage for your smart technology through a homeowners insurance endorsement or a separate insurance policy. Both a standalone personal articles floater and a scheduled personal property coverage add-on to your home insurance policy allow you to secure coverage against additional perils and raise your coverage limits for select valuables, potentially including robots, in exchange for accepting higher premium costs.
You may also be able to buy a standalone electronics insurance policy to cover your smart home devices, such as thermostats, smoke detectors and security systems. These types of protection plans from robotics companies may cover damage from mechanical and electrical breakdowns, which usually aren’t covered by standard homeowners insurance.[3]
It’s also worth noting that some large corporations, like GE and Ocado, have taken out commercial robot insurance policies to cover damage to robotic equipment and robot-related legal liability claims.[4] Although dedicated robot coverage like this is not commonly offered to homeowners as of yet, it’s possible that the home insurance industry could develop a similar insurance product as domestic robots become more common in the future.
How To Get Home Insurance Coverage for Your Robot
The best way to find the right homeowners insurance coverage for your high-tech possessions is to shop around and compare quotes from three to five different insurance carriers. This can be burdensome, though, since it will take a long time to contact multiple insurance companies separately so you can give them your information.
However, insurance shopping becomes significantly easier when you go through SmartFinancial. Once you answer a few questions, our technology platform will connect you with the best insurance options for your circumstances. Click here to get started on comparing home insurance quotes for free.
- Insurance quotes /
- Home /
- Home Insurance And Robots
Dylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health and life insurance under his belt. He has over nine years of experience writing for online publications, primarily about gaming and esports. In the process, he has become an expert in search engine optimization, news reporting, feature writing and copy editing.


Get a Free Home Insurance Quote Online Now.
More on Home Insurance

Looking for Home Insurance?
Compare rates from dozens of companies in less than 3 minutes.