

Business Personal Property Insurance: Coverage, Costs and How It Works
 Written by Dylan Tate Dylan TateDylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health a... Read more |  Edited by Richard Murphy Richard MurphyRichard Murphy manages content on SmartFinancial's website. With a strong background in content strategy and copywriting... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
Business personal property insurance is a type of commercial coverage that insures furniture, equipment, inventory and other items used by your business against damage from sudden perils, like storms and fires. Generally, the best way to obtain BPP coverage is to purchase commercial property insurance or a cost-effective business owners policy.
Keep reading to learn more about business personal property insurance coverage, including what other perils it covers and how much it may add to your monthly business insurance premium.
|
Key Takeaways
|
On This Page

What Is Business Personal Property Insurance?
What Does Business Personal Property Insurance Cover?
What Isn’t Covered by Business Personal Property Insurance?
Business Personal Property Insurance vs. Business Owners Policy
How Much BPP Insurance Does My Business Need?
How Much Does Business Personal Property Insurance Cost?
Who Needs Business Personal Property Insurance?
Business Personal Property Insurance at a Glance
How To Get Business Personal Property Insurance
FAQs

What Is Business Personal Property Insurance?
Business personal property insurance is a commercial insurance product that covers sudden and unexpected damage to the physical, portable property your business uses. It is automatically included in a standard commercial property insurance or business owners policy, though some insurers may also offer it as a separate insurance product.[1]
| Insurance Product |
Coverage |
|---|---|
|
Business personal property (BPP) insurance |
Damage to commercial items only |
|
Commercial property insurance |
Damage to commercial items and buildings |
|
Business owners policy (BOP) |
Damage to commercial items and buildings — plus business interruptions and general liability claims |
How Does BPP Insurance Work?
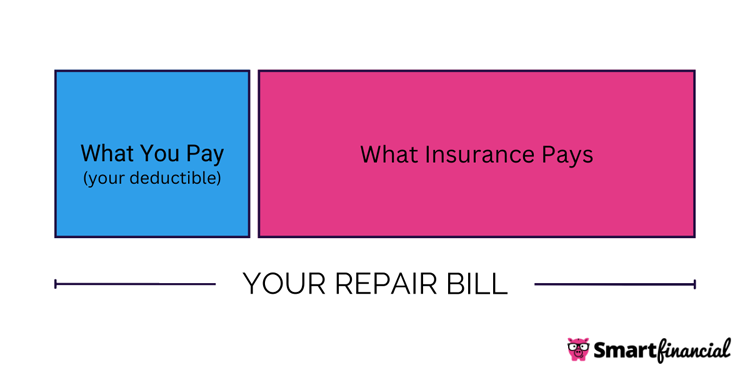
When you file a claim on your business personal property insurance, you generally have to cover a portion of the costs yourself in the form of a deductible.[2] For example, if you experience $4,000 worth of covered property damage but have a $1,000 deductible, your insurance payout would only be $3,000. Even so, maintaining BPP insurance coverage can help prevent a major peril from putting you in severe debt — or out of business completely.
What Does Business Personal Property Insurance Cover?
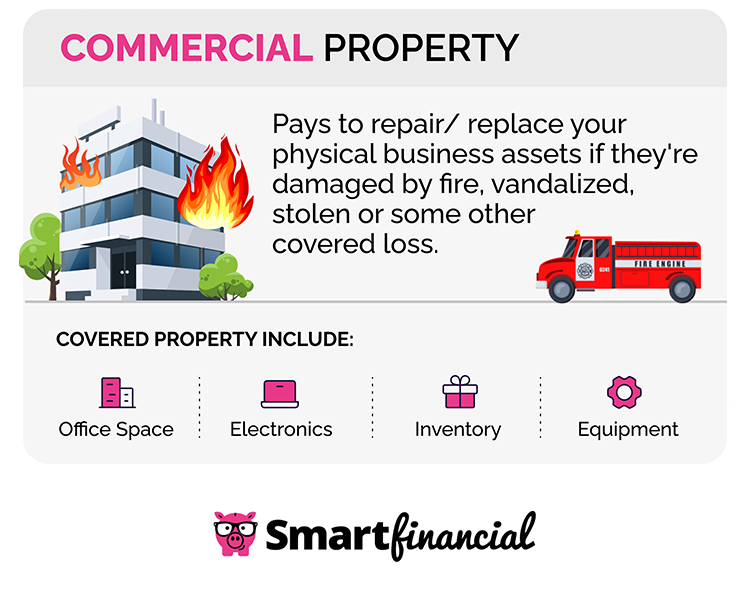
A business personal property insurance policy can cover several types of items that your business owns or otherwise uses, such as the following:[1][3]
- Office furniture and furnishings
- Office supplies
- Computers and other electronic hardware
- Machinery
- Upgrades and installations added to your commercial building
- Tools and equipment
- Inventory
- Accounts receivable documentation and other documents
- Outdoor landscaping and other structures, like fences
Business contents are generally covered while they are inside your commercial building and when they are out in the open or in a car within 100 feet of your business premises.[1] Special form policies provide open peril coverage extending to any cause of loss not specifically excluded by the policy. Conversely, named peril policies may only insure your company’s personal property against the following perils:[4]
- Fire or lightning
- Explosion
- Windstorm or hail
- Smoke
- Damage by aircraft or vehicle
- Riot or civil commotion
- Vandalism
- Sinkhole
- Building collapse
- Volcanic eruption
- Automatic sprinkler leakage and some other types of liquid damage
Replacement Cost vs. Actual Cash Value
When you purchase business personal property coverage, you may have the option to insure your commercial contents at their actual cash value or replacement cost value. If a covered item is destroyed by a covered peril, an ACV policy will reimburse you at the item’s current market value. This takes into account how the item has depreciated since you first obtained it, meaning your insurance payout may not be enough to replace it.
Alternatively, an RCV policy will pay out whatever it would cost to replace your item with a comparable item after a covered loss. Since RCV payouts are generally higher, these policies are often more expensive. Keep in mind that some insurance carriers may require you to try to get damaged items fixed within six months of the damaging peril before they will agree to pay for replacement items.[1]
What Isn’t Covered by Business Personal Property Insurance?
While some BPP insurance policies cover theft, others may exclude coverage for losses related to robbery or burglary.[3][4] In addition, standard business personal property insurance policies usually don’t cover these perils:[4]
- Equipment breakdowns
- Wear and tear
- Floods and earthquakes
- War and nuclear hazards
- Power failure
- Pollution
- Changes in humidity or temperature
- Unexplained disappearance
A standalone BPP policy won’t cover the physical structure of your office building, but this coverage is included within commercial property insurance and business owners policies.[5] Also, standalone BPP insurance may not cover indirect losses stemming from property damage, such as lost income. These indirect losses may instead be covered by business interruption insurance, which is included in BOPs and some standalone commercial property policies.[1]
Certain items that were once covered by your BPP insurance may cease to qualify for coverage if you no longer use them for commercial purposes.[1] Finally, your property insurance policy generally won’t cover business-owned vehicles or items in transit. These are instead covered by commercial auto insurance and inland marine insurance, respectively.[6]
Business Personal Property Insurance vs. Business Owners Policy
When deciding whether your business needs the more complete protection offered by a BOP or whether BPP insurance alone would suffice, consider the following differences between these types of policies:[7][8][9]
|
|
Business Personal Property Insurance |
Business Owners Policy |
|---|---|---|
| Covered Losses | Damage to commercial items, including equipment, inventory and furniture | Same as BPP insurance — plus damage to commercial buildings, interruptions of normal business operations and third-party bodily injury, property damage or personal and advertising injury claims |
| Average Annual Cost | Starting around $215 | $500 to $3,000 |
| Recommended For | Businesses that primarily need coverage for portable, physical assets | Any small business without specialized risks |
| Other Benefits | May allow you to save money while forgoing unnecessary coverages | Bundled policy means all claims and payments are conveniently handled by the same insurer |
Is BPP Insurance the Same as Commercial Property Insurance?
Business personal property insurance is a subset of commercial property insurance, so it does not provide the same level of coverage on its own. While BPP insurance only covers damage to the contents of your commercial buildings, commercial property insurance also includes coverage for the buildings themselves and, in some cases, business interruptions caused by covered property damage.[5]
How Much BPP Insurance Does My Business Need?
Many commercial property insurance policies include a coinsurance provision, meaning you must set your coverage limit at a certain percentage of the total value of your business property — usually ranging from 80% to 100%. As a result, if your BPP coverage limit is equal to 70% of the value of your business contents, your insurer may not fully cover your claims — even if the value of those claims is lower than your policy’s coverage limit.[10]
How Much Does Business Personal Property Insurance Cost?
BPP coverage is included in commercial property insurance, which costs $800 to $5,000 per year on average — though you will likely pay less if you opt for a policy that only includes coverage for business personal property.[8] For example, low-risk businesses may be able to get commercial property coverage from ERGO NEXT Insurance for as little as $18 per month.[7]
That said, you can generally secure more comprehensive and cost-effective protection for your commercial enterprise by purchasing a business owners policy. BOPs cost an average of $500 to $3,000 per year, and they typically come with business personal property, commercial building, business interruption and general liability insurance coverage.[8]
Who Needs Business Personal Property Insurance?
Businesses that own physical property typically need business personal property insurance, though its importance may vary by industry. For example, a retail store owner may be unable to financially recover from a peril that destroys all their inventory without BPP insurance. Conversely, a remote software developer whose work is saved in the cloud may only need to replace their laptop after a damaging peril, which they may be able to afford out of pocket.
Most businesses would likely benefit from a complete commercial property insurance policy, but standalone BPP coverage may make sense if you operate a home-based business. Although homeowners insurance covers the structure of your home, it may provide little or no coverage for commercial property — meaning you may need separate coverage for your business items but not commercial building coverage.[11]
Business Personal Property Insurance at a Glance
- Business personal property (BPP) insurance covers sudden damage to the items your business owns, rents or leases — including inventory, equipment, documents and furniture.
- For more complete protection, consider commercial property insurance, which covers both commercial items and buildings, or business owners policy (BOP) insurance, which adds general liability and business interruption coverage to commercial property insurance.
- Standalone BPP insurance is not always available or practical, but it may be worth looking into if you run a home-based business and don’t need commercial building coverage.
- BPP insurance rates may start as low as $18 per month, but your premiums will ultimately depend on factors like the value of your property, the level of risk your business faces and whether your policy includes additional coverage types.
How To Get Business Personal Property Insurance
Shopping for business personal property insurance should involve analyzing quotes from three to five unique insurance carriers. You’ll need to provide insurance companies with quite a bit of information about your business, like its industry, location, revenue, payroll and more. All of this can make for a tiresome process if you try to reach out to insurance companies one at a time.
That’s why the best option is to comparison shop through SmartFinancial. You’ll only need to answer a single set of questions before we match you with an agent who can help you find the best BPP, commercial property or business owners policy given your budget and coverage needs. Click here to start comparing business insurance quotes for free today!
- Insurance quotes /
- Commercial /
- Business Personal Property Insurance
Dylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health and life insurance under his belt. He has over nine years of experience writing for online publications, primarily about gaming and esports. In the process, he has become an expert in search engine optimization, news reporting, feature writing and copy editing.


Get a Free Commercial Insurance Quote.
More on Commercial Insurance

Looking for Commercial Insurance?
Compare rates from dozens of companies in less than 3 minutes.