

What Is Property and Casualty Insurance?
 Written & Edited by Dylan Tate Dylan TateDylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health a... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
Property and casualty insurance is an umbrella term for various insurance products that can reimburse you if your property is damaged by a sudden peril or shield you from costly expenses if you are sued or otherwise held liable for someone else’s loss. It can include both personal lines policies for individual property owners and commercial insurance policies for business owners.
Read on to learn more about property and casualty (P&C) insurance, such as what types of coverage you may be required to purchase and when you may need insurance policies that don’t fall under the P&C umbrella.
|
Key Takeaways
|
On This Page

How Does Property and Casualty Insurance Work?
What Types of Property and Casualty Policies Are There?
What Does Property and Casualty Insurance Cover?
How Much Property and Casualty Insurance Do You Need?
How Much Does Property and Casualty Insurance Cost?
How To Get Property and Casualty Insurance
FAQs

How Does Property and Casualty Insurance Work?
When you take out a property and casualty insurance policy, you pay premiums to the insurance company in exchange for coverage for specific losses, like fire damage, theft or liability lawsuits. Logistically, the purpose of paying premiums is to divide the risk among all the policyholders, thereby reducing the risk for each individual. As a result, when you experience a covered loss, you can file an insurance claim so you don’t have to bear the full financial burden yourself.
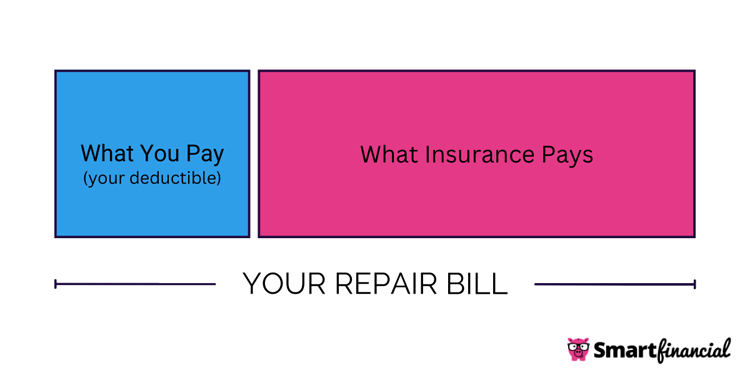
Keep in mind that many property and casualty insurance policies are subject to a deductible, which is a set amount of money that you are responsible for contributing toward each claim. For example, if you experience $2,000 worth of covered losses but have a $500 deductible, then your insurance payout would be $1,500. You should also note that, in this scenario, it would not make sense to file a claim unless your losses significantly exceed $500.
What Types of Property and Casualty Policies Are There?
The following are among the most common and significant types of property and casualty coverage:
- Homeowners: Homeowners insurance can reimburse you if your home, belongings or other structures on your property are suddenly damaged or destroyed. It also includes liability coverage that can take care of your legal expenses and other people’s medical bills or property repairs, along with coverage for additional living expenses in case you must temporarily move out of your house due to a covered peril.
- Auto: Auto insurance primarily serves the purpose of covering other people’s hospital or repair expenses after a crash you are responsible for. That said, your policy may also include coverage types that can pay for your own medical treatments or car repairs after an accident.
- Commercial: Commercial insurance encompasses a wide array of coverages that can provide a financial cushion for businesses in case their property is damaged or they are held liable for causing another person or business to experience some kind of loss.
- Umbrella: Umbrella insurance is a type of casualty insurance specifically designed to provide excess coverage in case a costly claim exhausts the limit of one of your other liability insurance policies.
There are numerous other insurance coverage types that fit partially or wholly within the property and casualty insurance designation, including these:
| Renters insurance | Condo insurance |
| Landlord insurance | Valuables insurance |
| Motorcycle insurance | RV insurance |
| ATV insurance | Snowmobile insurance |
| Boat insurance | Builders risk insurance |
| Pet insurance | Travel insurance |
| Flood insurance | Earthquake insurance |
Is Property and Casualty Insurance Required?
Some types of property and casualty insurance are required by law. For example, auto liability insurance is required for drivers in every state besides New Hampshire.[1] In addition, the majority of businesses with employees are required to maintain workers’ compensation insurance in every state except for Texas, South Dakota and Wyoming.[2]
Meanwhile, some coverage types that would otherwise be optional are often required if you need to take out a loan. For example, mortgage lenders typically require homeowners to purchase home insurance, and you may need comprehensive and collision car insurance to secure an auto loan.
What Does Property and Casualty Insurance Cover?
While coverage details can vary significantly depending on the type of policy you purchase, P&C insurance policies can generally be broken down into two types of coverage: property insurance and casualty insurance. Property insurance broadly refers to policies that cover your expenses after buildings, items and other types of property are suddenly damaged or destroyed. Examples of property insurance include the following:
| Dwelling coverage | Other structures coverage |
| Personal property coverage | Loss of use coverage |
| Flood insurance | Earthquake insurance |
| Service line coverage | Windstorm insurance |
| Physical damage auto insurance | Uninsured and underinsured motorist property damage coverage |
| Gap insurance | Rental car reimbursement coverage |
| Commercial property insurance | Business interruption insurance |
| Inland marine insurance | Equipment breakdown coverage |
| Pet insurance | Damaged baggage coverage |
Property insurance policies often insure the things you own at their actual cash value (ACV). This means your insurer will take depreciation factors into account when determining your insurance payout. However, if you’re willing to pay a higher premium, you can often upgrade to replacement cost value (RCV) coverage, which means your insurance carrier will pay you whatever it costs to replace your property after a covered loss.
Meanwhile, casualty insurance refers to policies that provide liability coverage, remedying other people’s losses that you are responsible for by covering expenses like hospital bills, property repairs, lost income and more. Additionally, liability insurance can typically cover legal expenses, such as attorney fees, judgments and settlements, if a liability claim escalates into a lawsuit. Examples of casualty insurance include the following:
What Isn’t Covered?
In general, P&C insurance is designed to cover sudden and unexpected losses, so your policies likely won’t cover gradual or predictable sources of damage, such as regular wear and tear or damage caused by neglect or poor maintenance. Likewise, you shouldn’t expect to receive any payment from your insurance company for intentional losses or other fraudulent behavior.
Remember that, although most insurance policies come with their own sets of exclusions, you may be able to secure protection against these exclusions by purchasing additional coverage. For example, standard homeowners insurance policies don’t cover floods or earthquakes, but you can buy separate flood or earthquake insurance if you live in a high-risk area.
Finally, P&C insurance generally won’t cover injury or death experienced by you or your family members due to natural causes, as health insurance and life insurance are not considered to be types of P&C coverage.[3] Similar coverage types, like disability insurance, dental insurance, vision insurance and long-term care insurance, also likely would not fall under the property and casualty umbrella.
How Much Property and Casualty Insurance Do You Need?
You’ll generally want to purchase enough types of P&C insurance with high enough coverage limits to adequately cover all of the risks you face in your day-to-day life. For example, it’s recommended that you purchase a home insurance policy with enough dwelling coverage to pay to completely rebuild your house if necessary and between $300,000 and $500,000 worth of personal liability coverage.[4]
Meanwhile, your state’s laws will dictate the minimum amount of car insurance you must purchase. However, it’s generally recommended that you get at least $100,000 worth of bodily injury liability coverage per person, $300,000 worth of bodily injury liability coverage per accident and $100,000 worth of property damage liability coverage, which is more than the minimum amount required by law in any state.[5]
Lastly, you should purchase enough commercial property insurance to cover the replacement cost of the most important buildings and items your business owns. In addition, you’ll want casualty coverage with limits high enough to protect your company’s most important assets, with the exact amount you need depending on your exposure to potential liability claims.
How Much Does Property and Casualty Insurance Cost?
As of March 2025, Americans pay an average of $2,242 per year for homeowners insurance and $2,678 per year for full coverage car insurance.[6][7] Meanwhile, small businesses pay an average of around $8,940 per year for business owners policies (BOPs) plus workers’ compensation and commercial auto insurance from The Hartford.[8]
Ultimately, how much you have to pay for any type of P&C insurance will depend on the details of your policy, including the coverage types and deductibles you select, and the likelihood that you will have to file a claim. Insurance companies may consider factors like your location, your claims history, the condition of your property, your liability exposure and more in the process of calculating the risk associated with covering you and setting your rates.
How To Get Property and Casualty Insurance
No matter what type of P&C insurance you’re looking for, it’s crucial to shop around and compare rates from multiple insurance providers so you can find the best possible deal on the coverage you need. Unfortunately, it can be tedious to individually reach out to three to five different insurers in order to give them all of the information they need to produce an accurate insurance quote.
Instead of sharing the same information over and over again, you should share it just one time with SmartFinancial. Once you fill out our online questionnaire, we’ll connect you with a qualified insurance agent who can help you sift through your options to find the right coverage for you. Click here to select the type of property and casualty coverage you need and start comparing quotes for free!
- Insurance quotes /
- Property And Casualty Insurance
Dylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health and life insurance under his belt. He has over nine years of experience writing for online publications, primarily about gaming and esports. In the process, he has become an expert in search engine optimization, news reporting, feature writing and copy editing.


Get a Free Insurance Quote Online Now.
More on Insurance
Get a Free Insurance Quote.
Compare rates from dozens of companies in less than 3 minutes.