

10 Things You Need To Do When Shopping for Car Insurance
 Written & Edited by Dylan Tate Dylan TateDylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health a... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
It’s crucial to shop around before you purchase an auto insurance policy since each insurance carrier has its own formula for evaluating risk, and one insurer may offer you the same coverage for a better price than another. Online comparison tools like SmartFinancial make it easy and efficient to shop for car insurance from multiple top insurance companies.
Read below for an overview of the steps you should take when shopping for car insurance, from compiling the information you’ll need when you apply to activating your new policy.
|
Key Takeaways
|


Why Is It Important To Shop for Car Insurance?
You shouldn’t necessarily purchase auto insurance from the first company you obtain a quote from because different insurers have different methods for calculating the risk associated with covering you. This means one insurance provider could view your specific set of circumstances more favorably than another, and it could offer you coverage at a lower rate as a result.
As you shop around, make sure you compare apples to apples rather than apples to oranges. For example, a cheap policy that only includes liability coverage is preferable to a more expensive liability-only policy with the same coverage limits from a different insurance carrier. However, it may not be better than a more expensive full coverage policy, depending on your coverage needs.
How To Shop for Car Insurance
By following these 10 steps, you can maximize the odds that you will find a car insurance policy that meets your needs at an affordable price.
1. Make Sure You Have the Right Information and Documentation
Whenever you reach out to an insurance company for a quote, you will generally need to share information such as the following:[1][2]
- Name and date of birth
- Sex
- Marital status
- Home address and, if different, the address where you will park your car
- Phone number and email address
- Vehicle year, make and model, body style and vehicle identification number (VIN)
- Vehicle mileage
- Date of vehicle purchase
- Driver’s license number
- Prior insurance history
- Ticket and accident history
- License suspension information
- Financing or leasing information
Keep in mind that you will likely need to provide the above information for every vehicle and person your policy will cover, including any cars owned or driven by you, your spouse or your driving-age children. Depending on your state, prospective insurers may also check your credit information when setting your rates, although you shouldn’t have to provide this information yourself.
2. Learn Your State’s Minimum Car Insurance Requirements
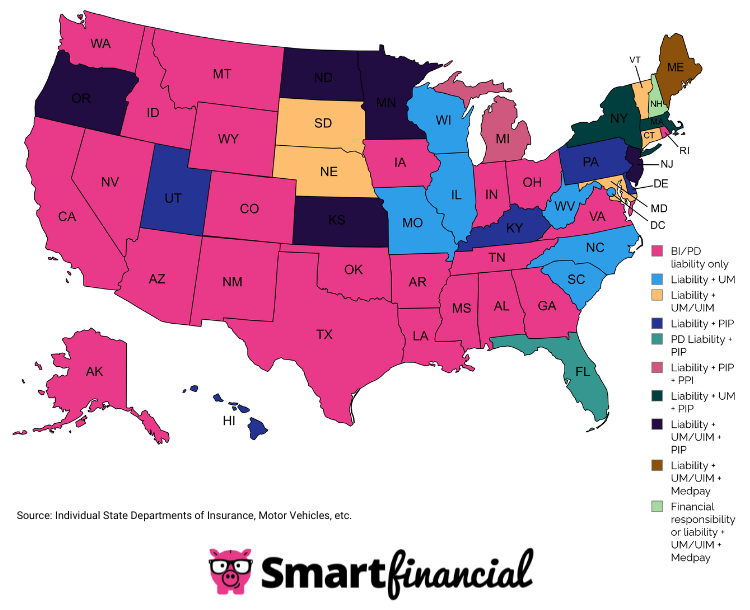
Car insurance is required by law in every state except for New Hampshire.[3] As a result, most drivers throughout the country will need to obtain a minimum amount of liability insurance and potentially other coverage types in compliance with their state’s laws. The following table goes over the coverage types that are most commonly required by state law, along with the range of mandatory minimum coverage limits that apply to most drivers across the nation.[4]
|
Coverage Type |
Range of Minimum Coverage Limits |
|---|---|
|
$15,000 to $50,000 per person, $30,000 to $100,000 per accident |
|
|
$5,000 to $25,000 per accident |
|
|
Uninsured/underinsured motorist bodily injury coverage |
$20,000 to $50,000 per person, $40,000 to $100,000 per accident |
|
Uninsured/underinsured motorist property damage coverage |
$5,000 to $25,000 per accident |
|
Personal injury protection (PIP) |
$3,000 to $250,000 |
3. Identify What Type of Coverage You’ll Need
While you are technically allowed to drive as long as you purchase enough car insurance to satisfy your state’s legal requirements, you may want to consider buying a policy with higher coverage limits and more coverage types than is required by law.
For example, it’s generally recommended that you purchase $100,000 worth of bodily injury liability insurance per person, $300,000 worth of bodily injury liability insurance per accident and $100,000 worth of property damage liability insurance, even though no state requires drivers to buy that much coverage.[5]
In addition, you will likely have to maintain comprehensive and collision insurance if you are financing or leasing your vehicle. Other coverage types that are generally optional but may still be worth considering include gap insurance, roadside assistance and rental car reimbursement coverage.
4. Compare Car Insurance Quotes and Policies
The best way to shop for car insurance that matches your needs and budget is to compare car insurance rates from at least three to five different insurance companies. The simplest and most effective way to compare insurance policies is by going through an independent marketplace, like SmartFinancial. We only need you to fill out a single questionnaire before we share your information with agents who can provide you with auto insurance quotes at no charge.
5. Ask Providers for Car Insurance Discounts
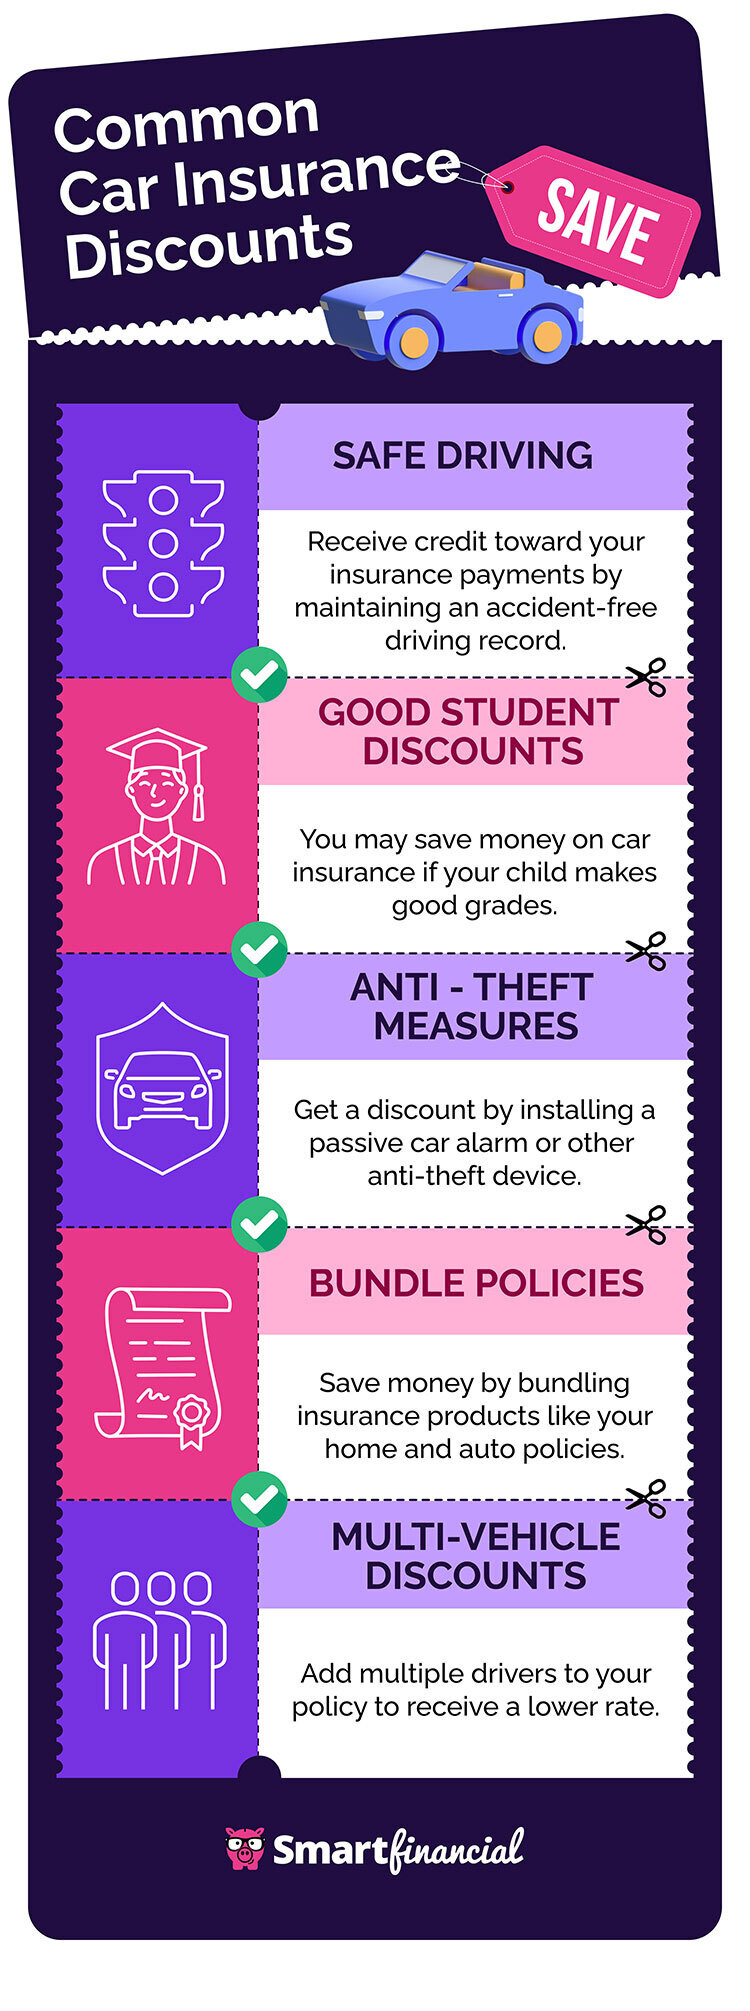
Before settling on an insurance carrier, you should ask each company whether it offers any car insurance discounts you might be eligible for. Even if one insurance company can offer you a lower base rate, another could end up providing a cheaper policy overall if it offers more discounts that you qualify for.
Some of the actions you could take to potentially earn a discounted car insurance rate include the following:
- Adding multiple cars to the same policy
- Installing anti-theft devices and other safety features
- Maintaining a clean driving record
- Taking an approved defensive driving course
- Getting good grades in school
- Paying your premiums in full at the beginning of your coverage period
- Practicing safe driving behaviors, as measured by a telematics device
- Purchasing a new vehicle
- Buying a new insurance policy or renewing your existing one before it expires
- Joining an approved church, company, university or organization to get an affinity discount
- Staying with your current insurer for several years to earn a loyalty discount
- Using an electronic funds transfer (EFT) or some other preferred payment method to pay your premiums
- Driving a hybrid or electric vehicle
6. Be Transparent
It’s important to be transparent with your insurance company, regardless of your circumstances. Although it could be tempting to conceal information that could cause your rates to go up, like how many traffic citations you’ve received or how often you drive your car, misleading your insurance provider will likely cost you more in the long run.
Purposefully lying to an auto insurance company for your own benefit is considered insurance fraud. If you are caught, your insurance carrier could cancel your policy or refuse to pay you after you file a car insurance claim, and you could even face criminal penalties, including fines and jail time.
7. Consider Bundling
If you’re struggling to choose among different insurance companies, consider that many insurers offer bundling discounts, allowing you to save money if you purchase multiple insurance products from the same carrier. For example, if two separate insurance providers offer you similar car insurance quotes but one of them offers you a better home insurance quote, it may make sense to buy both coverages from that insurer so you can bundle your policies together.
8. Know Your Budget
When deciding the coverage types, limits and deductibles you want your car insurance to include, it’s important to evaluate how these will affect the cost of the policy and whether it fits into your budget. For example, you may be tempted to select the highest deductible possible because it will lead to a lower auto insurance premium, but this could end up putting you in debt if you need to file a claim and can’t afford to pay your deductible.
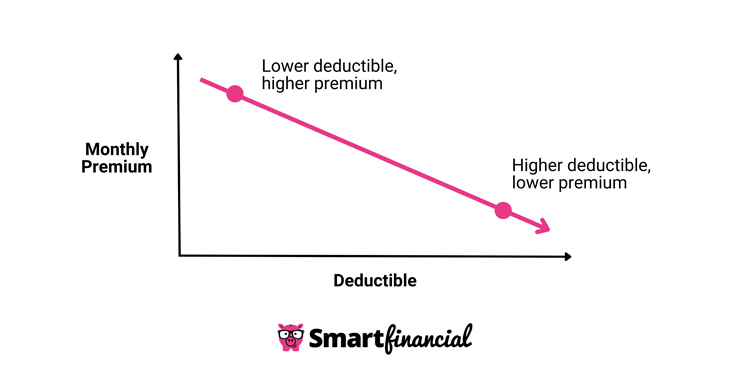
Conversely, if you have a great deal of money in savings but your regular income is relatively low, it may be easier to work a high-deductible, low-premium car insurance policy into your monthly budget. Ultimately, the purpose of insurance is to protect you from sudden and unexpected financial losses, so you need to strike a balance between maintaining enough coverage and keeping yourself from being dragged down by burdensome premiums.
9. Buy Your Car Insurance Policy
Once you have settled on the right insurance company and the amount of coverage you need, you will be ready to purchase your new car insurance policy. You can activate your policy with an upfront payment, which will usually be the premium for your first month of coverage. To avoid a lapse in coverage that could raise your rates in the future, you should set up your new policy so that it begins before your existing policy expires.
10. Shop for Car Insurance Annually
Your coverage needs can change over time, as can the factors that impact your car insurance prices, which is why it’s recommended that you review your insurance coverage and consider shopping around at least once a year, even if you’re happy with your current policy.[6] Regularly and thoroughly comparison shopping helps you make sure you never pay more for auto insurance than you have to.
What Factors Affect Rates When Shopping for Car Insurance?
Auto insurance companies may take the following factors into account when setting your car insurance rates:
- Location
- Driving record
- Vehicle make and model
- Vehicle use and mileage
- Policy details
- Prior claims
- Insurance history
- Applicable discounts
Insurers could also potentially consider personal details, like your age, sex, marital status and credit score, to determine your auto insurance rates. However, some states have laws that restrict the ability of car insurance companies to use these characteristics as rating factors.
- Insurance quotes /
- Auto /
- Shop Car Insurance
Dylan Tate is an insurance content expert for SmartFinancial with over 300 articles about home, auto, business, health and life insurance under his belt. He has over nine years of experience writing for online publications, primarily about gaming and esports. In the process, he has become an expert in search engine optimization, news reporting, feature writing and copy editing.


Get a Free Auto Insurance Quote Online Now.
More on Auto Insurance

Looking for Auto Insurance?
Compare rates from dozens of companies in less than 3 minutes.