

7 Ways To Reduce the Costs of Commercial Auto Insurance
 Written by Preston Micalizio Preston MicalizioPreston Micalizio writes insurance content for SmartFinancial. He brings three years of professional experience writing ... Read more |  Edited by Dan Marticio Dan MarticioDan Marticio is the content manager at SmartFinancial and has written 150+ articles across multiple insurance verticals.... Read more |
 Editorial Standards
SmartFinancial Offers Unbiased, Fact-based Information. Our fact-checked articles are intended to educate insurance shoppers so they can make the right buying decisions. Learn More
Check out what other insurers offer for policies, keep your driving record clean and take advantage of bundles and discounts to help save on commercial car insurance. Considering that commercial auto insurance premiums can be expensive, with some policies costing hundreds of dollars a month, finding areas where you can help reduce your costs is critical.
Keep reading to learn ways to save on a commercial auto insurance policy and what to avoid doing that might otherwise leave savings on the table.
|
Key Takeaways
|


How To Reduce the Costs of Commercial Car Insurance
Below, we’ll discuss various tips for reducing commercial car insurance costs.
1. Shop Around and Compare Quotes
Shopping around can help you discover what other commercial car insurance companies offer. This lets you compare options and see which carrier offers the best rates and benefits, helping you achieve your ideal policy.
Since insurance companies often use different methods of calculating risk, some factors could weigh more heavily with one company than others. For example, one company may offer the lowest rates for safe drivers, while another may offer the cheapest rates for high-risk drivers. Others may offer more benefits or lower costs if you have a fleet of commercial vehicles.
2. Maintain a Clean Driving Record for Your Business Fleet
Keeping your driving record clean helps prevent your insurance costs from climbing, as moving violations or accidents may signal to insurers that you’re at higher risk of making a claim. To offset this anticipated cost, many insurers raise your premiums.
Keep in mind that commercial auto insurance companies may only look at the previous three to five years of your driving history.[1] If you’re paying higher rates due to a recent accident, you may see your rates drop if you avoid any more marks on your driving record until this lookback period is over.
3. Invest in Driver Safety Training
Driver safety training can help drivers learn the most effective prevention methods, better avoiding accidents and insurance claims. For example, these courses may teach them what type of inclement weather to avoid driving in and how to always perform a routine maintenance check before driving at the start of their shift or after a break. Additionally, training can help inform them what to do when an emergency occurs on the road, such as if they get a flat tire or their brakes begin to malfunction.
4. Opt for Higher Deductibles (When Appropriate)
Increasing your deductible can lower your monthly premium, although you take on a higher out-of-pocket cost when filing a claim.
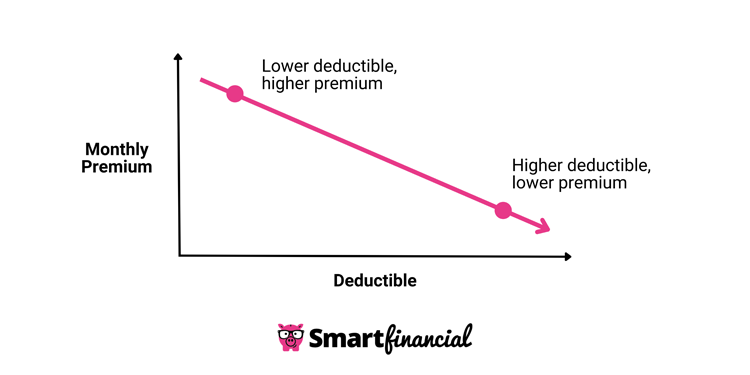
However, don’t forget that raising your deductible too high could result in financial burdens if you get in an accident or one or more of your cars are damaged. For example, if you had a $1,000 deductible but your car received $5,000 worth of damage due to bad weather, like hail, you would be responsible for the first $1,000.
This can compound with a fleet of cars, as each may come with a separate deductible, even if they’re damaged by the same event. For instance, if a fleet of 10 vehicles with the same $1,000 deductible received equivalent levels of damage, you could face $10,000 out of pocket. Keep these potential expenses in mind when raising your deductible.
5. Bundle Insurance Policies
You can often lower your business auto insurance costs by bundling different policies under the same insurer. For example, you can usually bundle your commercial auto and a commercial general liability policy.
If you’re a small to medium-sized business, check if your insurer offers a commercial package policy. This can offer a customized assortment of commercial policies, such as commercial auto, business interruption, professional liability and more, that often come at a reduced price than if you got each policy piecemeal.
6. Take Advantage of Discounts
Discounts can be a great way to lower your premium. Some potential discounts for commercial car insurance may include:
- Paid in full discount: While paying your commercial auto insurance premium monthly helps break an annual or six-mont commercial auto policy into manageable payments, paying in full at the start of your policy may come with a discount.
- Multi-vehicle discount: Adding more cars to a single policy gives your insurer more business, and you’ll often receive a discount. This can be especially useful to those with a fleet of vehicles.
- Loyalty discount: Remaining with the same insurance provider for an extended period may come with lower rates, as some insurers reward their policyholders for their loyalty. However, if you decide to move to another provider for better rates or other reasons, you’ll likely lose this discount and need to rebuild your loyalty with your new insurer from scratch.
- Good driver discount: If you maintain a good driving record by avoiding accidents and other incidents where you’d make a claim, you’ll likely get a discount to acknowledge that lower risk. Keep in mind that if you employ others to drive for your business, their driving history can also be considered.
- Business experience discount: One way to indicate you’re less of a risk is to have been in business for some time and maintained a good business track record, which may qualify you for a discount.
- Proof of prior insurance discount: If you're a business startup or have little experience, you may still qualify for a discount by showing that you’ve maintained other insurance coverage for an extended period with no gaps.
7. Implements Telematics or Usage-Based Insurance
Similar to telematics in personal auto insurance, many commercial car insurance company use telematics to lower costs for businesses with low-risk drivers. They can give you direct access to your driver’s performance through GPS tracking, onboard sensors and vehicle readings, such as speed, mileage and fuel consumption. This data is often available in real time through wireless uploads. You can use telematics data to augment your instruction to drivers and help your insurer determine rates based on proven safety that can result in lower rates.
This can be a good option if you rarely use your vehicle for commercial purposes, as a standard policy may cover more than you need and cost more. Check with your insurer to see if they offer usage-based commercial insurance and if it fits your needs.
What To Avoid When Trying To Cut Commercial Car Insurance Costs
Here are a few suggestions on what to avoid when looking to lower your commercial car insurance costs:
- Don’t forget to do a background check before hiring drivers, taking a close look at their driving histories. Even if it doesn’t immediately affect your premiums, a higher risk from a driver could lead to a future accident that would likely affect your premium.
- Don’t overlook discounts, as their savings often add up over time, even if it doesn’t feel worth the effort to research and ask your insurer about.
- Don’t forget to check out other commercial car insurance options. Even if you’re somewhat satisfied with your current insurance, there may be better rates that you could bring to your current insurer to negotiate for a lower premium.
- Enforce taking safety precautions like regularly maintaining your business vehicle and ensuring critical repairs are done as soon as issues are spotted, such as a thinning tire tread or corroding battery. While taking your business car into the repair shop may feel like a hassle, avoiding doing so could lead to an accident or damage that increases your rates.
How To Find the Right Commercial Auto Coverage for Your Business Needs
Shop around between three to five insurance companies to get an understanding of their rates, asking about discounts they may offer to see if you can further lower your monthly premiums. If you’ve implemented safety training or telematics, you can use that data to help show you’re less of a risk and potentially keep your costs lower. Keep in mind that you’ll need to go through each insurer one by one, providing details on your fleet and any drivers so they can assess your risk.
This process may be a hassle and eat up your time, so consider speeding things up using an insurance marketplace like SmartFinancial. After answering a brief questionnaire, we can connect you with a licensed insurance agent who can help you get commercial coverage that meets your business needs. Click here to get started on a free commercial auto insurance quote today!
- Insurance quotes /
- Commercial /
- Save On Commercial Car Insurance
Preston Micalizio writes insurance content for SmartFinancial. He brings three years of professional experience writing in various industries, from higher education to e-commerce. He strives to engage with the audience, provide accurate reporting and make complex subjects easily digestible.


Get a Free Commercial Insurance Quote.
More on Commercial Insurance

Looking for Commercial Insurance?
Compare rates from dozens of companies in less than 3 minutes.